FPA Insights | September 2026
One of the reasons for FPA New Income Fund’s long-term success is its uncommon flexibility. Few other bond funds in its Morningstar Short-Term Bond category can and have varied their duration (interest rate sensitivity), credit quality, and sector exposure as much over the past decade.
Its sector flexibility was highlighted again recently: After nearly 20 years, the investment team added exposure to Treasury Inflation-Protected Securities (TIPS) in the second quarter.
5-year TIPS recently had a real yield in excess of 2.5% and have only been cheaper less than 1% of the time over the last decade through September 21, 2026:
Market Yield on U.S. Treasury at 5-Year Constant Maturity
(Quoted on an Investment Basis, Inflation-Indexed). As of September 21, 2026.
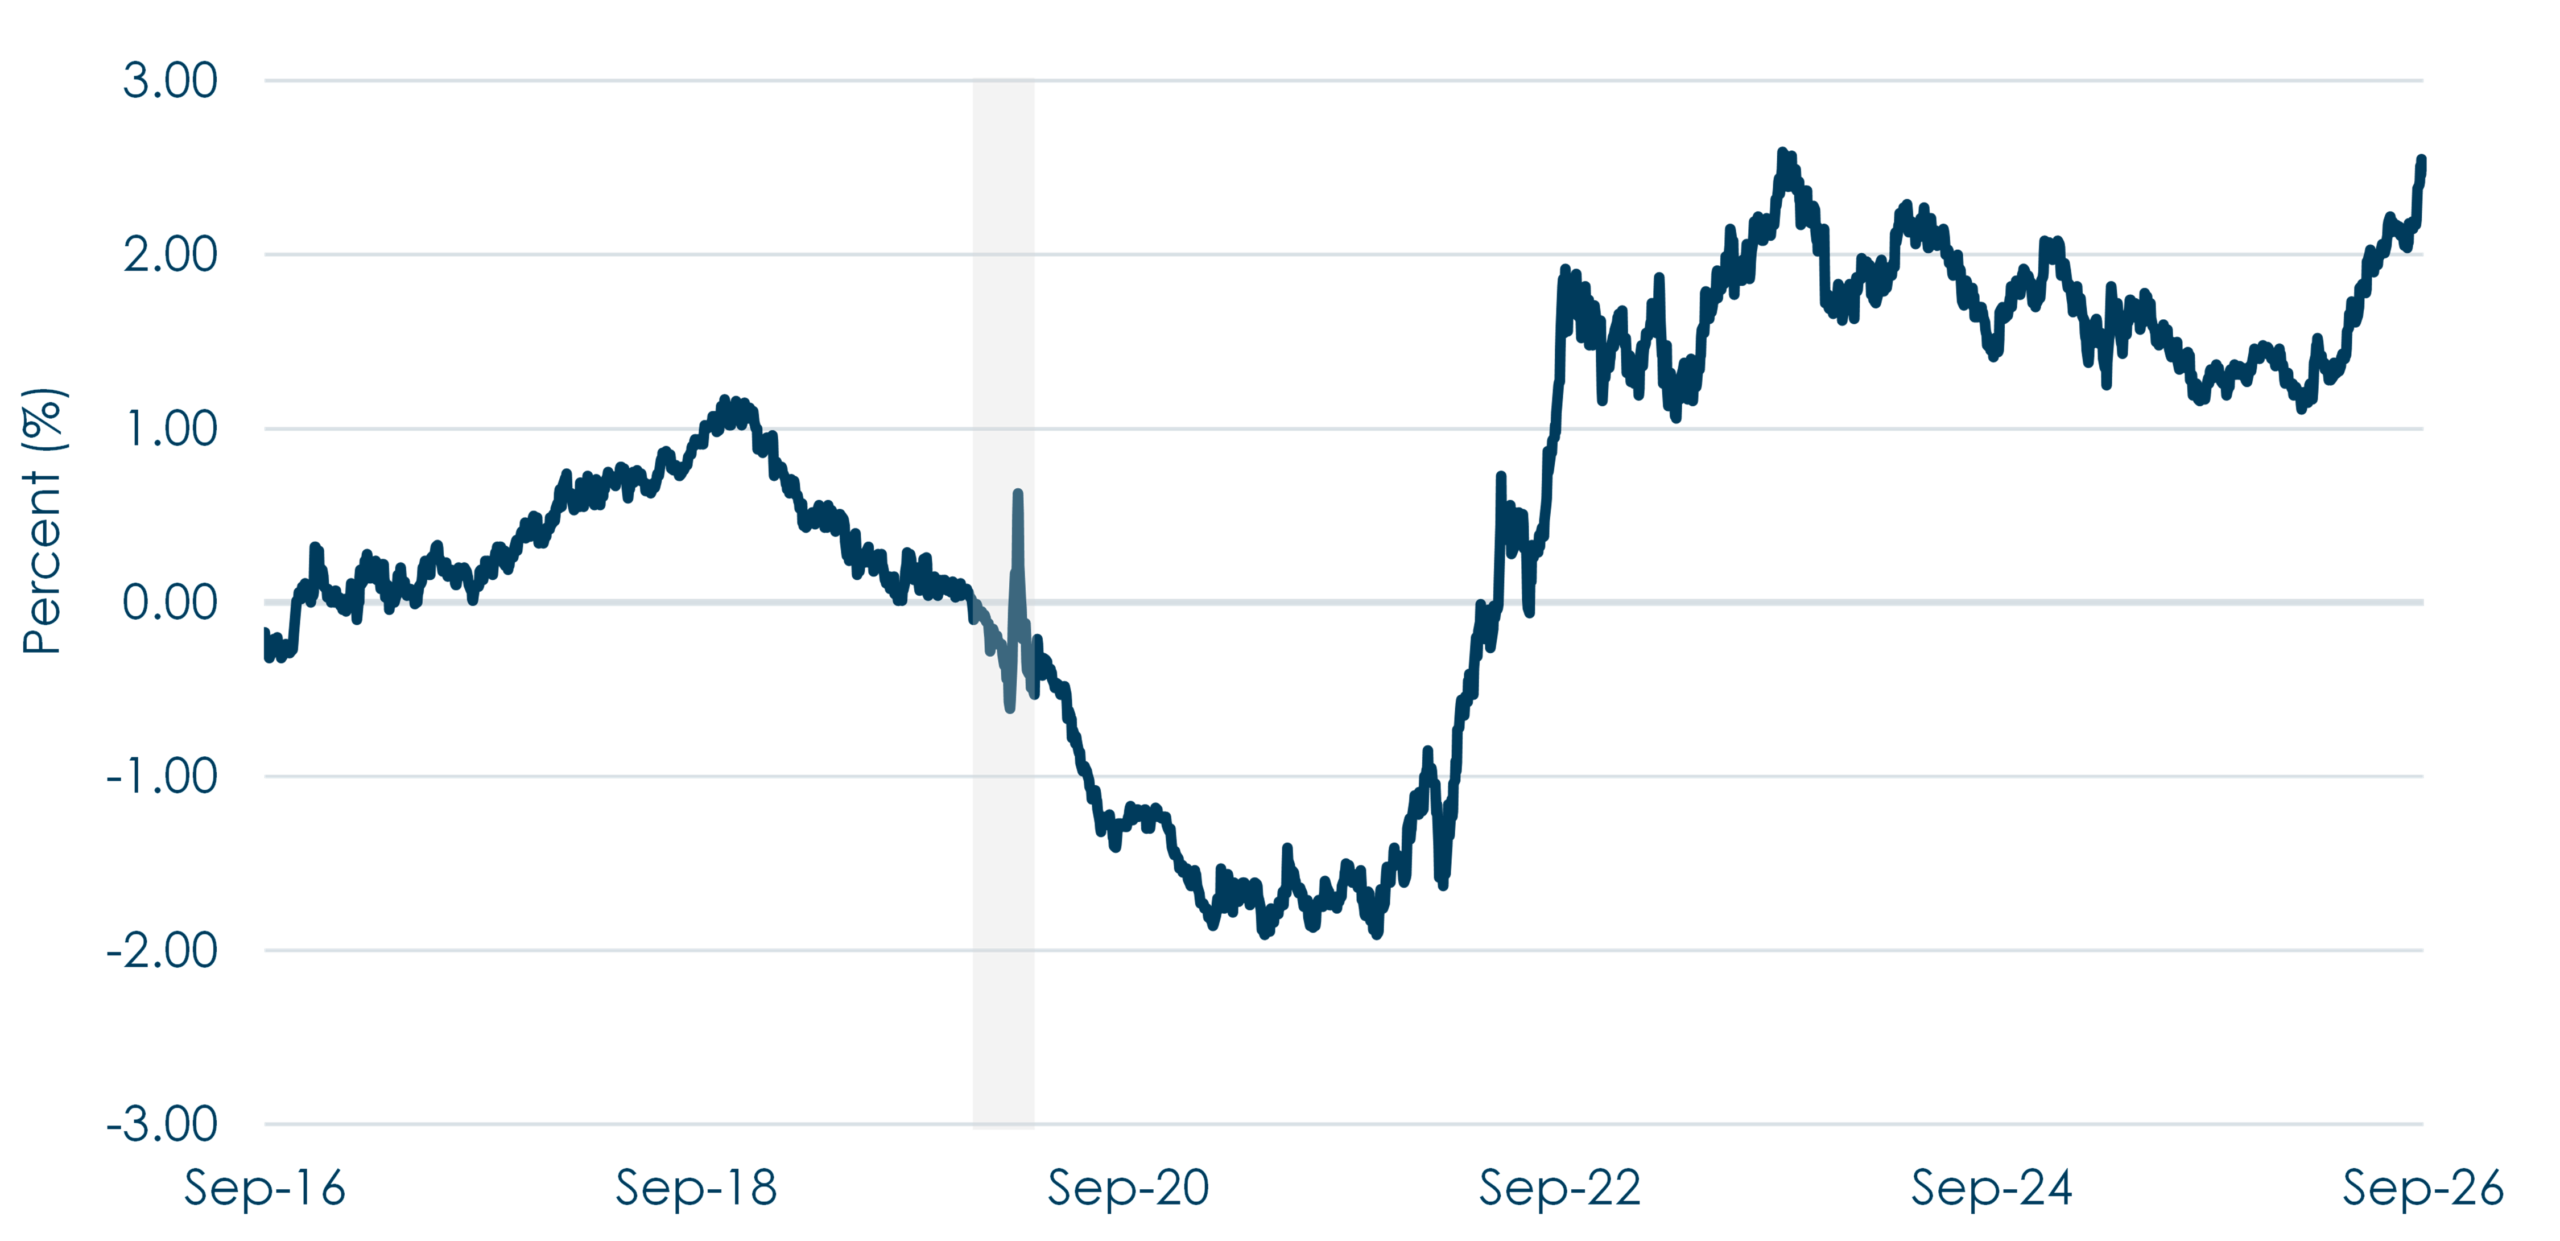
Shaded areas indicate U.S. recessions.
Source: Board of Governors of the Federal Reserve System (US), Market Yield on U.S. Treasury Securities at 5-Year Constant Maturity, Quoted on an Investment Basis, Inflation-Indexed [DFII5], retrieved from FRED, Federal Reserve Bank of St. Louis; https://fred.stlouisfed.org/series/DFII5.
To learn more about the team’s thinking on TIPS, please see the excerpt below from their recent quarterly letter:
“… we initiated a new position in five-year maturity TIPS during the quarter. Like a typical Treasury bond which is known as a nominal Treasury (“Treasury”), TIPS are backed by the full faith and credit of the United States government. Treasuries pay a fixed rate of interest on a fixed principal balance. TIPS also pay a fixed rate of interest but on a principal balance that grows at the rate of inflation (or shrinks at the rate of deflation). The yield on a Treasury (referred to as the nominal yield) can simplistically be broken down into two pieces – a real yield over the life of the Treasury plus the expected inflation over the life of the Treasury. In other words, when buying a Treasury, one is buying a fixed real yield and a fixed amount of inflation. To the extent that real yields and/or expected inflation change during the five-year life of a Treasury, the nominal yield and thus the dollar price of the Treasury will change. On the other hand, the real yield of TIPS is fixed and the inflation component of the TIPS future return will “float” based on actual inflation over time. As a result, the dollar price of TIPS will respond to changes in real yield.
Looking backward, actual inflation over a five-year period can differ from the inflation that was expected at the beginning of the five-year period. Over the life of a Treasury, if actual inflation is higher than the inflation expected at the time of the Treasury investment, then the total real return over the life of the Treasury will be less than the real yield at purchase. In comparison, over the five-year life of the TIPS, the realized real return should be similar to the real yield at purchase, regardless of actual inflation over those five years. It stands to reason then that one might want to buy TIPS if one has a view that actual inflation will be higher than the expected inflation that is embedded in the yield of the Treasury. As an example, at June 30, the nominal yield on the 5-year nominal Treasury was 4.23%. The real yield on the 5-year TIPS was 1.95%. The implied inflation expected over the next five years was 4.23% less 1.95%, or 2.28%. If one had a view that inflation over the next five years would be greater than 2.28%, it may make sense to buy TIPS instead of Treasuries and vice versa.
So what is our view on inflation? It should surprise no one that we do not have a view on inflation. We have written many times before that macroeconomic and market predictions do not drive our investing process because we believe investing in that manner is a low conviction way to produce attractive long-term risk-adjusted returns. How then did we choose to buy TIPS? It’s quite simple: at our purchase prices, we found that TIPS offered an attractive absolute return over a range of real interest rate and inflation scenarios in the short (12 months) and long (5 years) term. In the short-term, TIPS may produce an attractive positive absolute return while underperforming a Treasury in some scenarios (think very low inflation and very low real interest rates) but may alternatively produce an attractive positive return and outperform a Treasury in other scenarios (think elevated inflation and rising real interest rates). Further, consistent with our investment process, even when assuming very low inflation, we believe we purchased TIPS at prices that would produce at least a breakeven return over twelve months if real interest rates were to increase by 100 bps during that time. In short, much like our prior investments in Treasuries and our investments in any other type of debt, when considering what could happen in the future, we believe the TIPS offered an attractive upside-versus-downside and attractive long-term return without taking a view on what will happen in the future.
Our recent investment in TIPS is representative of our flexible and opportunistic investment approach. The last time the Fund owned TIPS was nearly 20 years ago. Since then, we have looked at TIPS many times but either the absolute short- and long-term return profile was not attractive to us or there were other uses of capital we believed had more attractive absolute return profiles. At June 30, 2026, 5-year real yields increased to levels last seen in 2022-2024. Due to higher spreads in 2022-2024, there were other uses of capital (mortgages, ABS, corporates, etc.) we believed would be more likely to maximize the return on that capital while also satisfying our desire for an expected return of capital. In the second quarter of 2026, with spreads in historically low territory, TIPS became an attractive use of capital.”
Read the full commentary for additional insights into the team’s investment outlook, portfolio positioning, and the decision to add TIPS for the first time in nearly 20 years.
Explore the FPA New Income Fund Brochure and additional resources:
IMPORTANT INFORMATION
FPA New Income Fund Performance as of 6/30/2026: 1 Year: 3.48%; 5 Years: 3.33%; 10 Years: 2.97%; Since Inception: 6.15%.
Fund performance shown is for the Institutional Class shares. Inception date for the FPA New Income Fund (the “Fund”) was July 11, 1984. Periods greater than one year are annualized. Past performance is no guarantee of future results and current performance may be higher or lower than the performance shown. This data represents past performance and investors should understand that investment returns and principal values fluctuate, so that when you redeem your investment it may be worth more or less than its original cost. Visit the Fund’s website at fpa.com or call toll-free, 1-800-982-4372, for current month-end performance data.
The Fund’s Total Annual Fund Operating Expenses before reimbursement (as of the most recent prospectus) is 0.59% for the Institutional Class and 0.77% for the Investor Class. First Pacific Advisors, LP (“FPA” or the “Adviser”) has contractually agreed to reimburse the Fund for Total Annual Fund Operating Expenses (excluding interest, taxes, brokerage fees and commissions payable by the Fund in connection with the purchase or sale of portfolio securities, and extraordinary expenses, including litigation expenses not incurred in the Fund’s ordinary course of business) in excess of 0.454% of the average daily net assets of the Institutional Class shares of the Fund through January 31, 2027, and in excess of 0.554% of the average daily net assets of the Investor Class shares of the Fund through January 31, 2027. This agreement may only be terminated earlier by the Fund’s Board of Trustees (the “Board”) or upon termination of the Advisory Agreement.
This communication is for informational and discussion purposes only and does not constitute, and should not be construed as, a recommendation, financial promotions, investment advice, encouragement or an offer or solicitation for the purchase or sale with respect to any securities, products, or services discussed, and neither does it provide investment advice. Any such offer or solicitation shall only be made pursuant to the relevant offering documents for an FPA Fund or other client account, which supersedes the information contained herein in its entirety. This communication does not constitute an investment management agreement or offering circular. The information and data presented has been prepared from sources believed reliable, but the accuracy and completeness of the information cannot be guaranteed and is not a complete summary or statement of all available data. You should not construe the contents of this communication as legal, tax, investment or other advice or recommendations.
You should consider the Fund’s investment objectives, risks, and charges and expenses carefully before you invest. The prospectus for the Fund details the Fund’s objective and policies, charges, and other matters of interest to the prospective investor. Please read the relevant Fund’s prospectus carefully before investing. The prospectus for the Fund may be obtained by visiting the website at fpa.com, by email at [email protected], toll-free by calling 1-800-982-4372 or by contacting each Fund in writing.
Any Fund data included herein represents past performance and investors should understand that investment returns and principal values fluctuate, so that when you redeem your investment it may be worth more or less than its original cost. As with any investment, there is always the potential for gain, as well as the possibility of loss.
The information contained herein reflects certain opinions and/or views as of the date provided, is subject to change without notice, and may be forward-looking and/or based on current expectations, projections, and/or information currently available. Such information may not be accurate over the long term. Actual results may differ from those anticipated. These opinions/views may differ across the portfolio managers and analysts of the firm as a whole and are not intended to be a forecast of future events, a guarantee of future results, or investment advice. FPA cannot assure future results and disclaims any obligation to update or alter any statistical data and/or references thereto, as well as any forward-looking statements, whether as a result of new information, future events, or otherwise. Future events or results may vary significantly from those expressed and are subject to change at any time in response to changing circumstances and industry developments.
Investments carry risks and investors may lose principal value. Capital markets are volatile and can decline significantly in response to adverse issuer, political, regulatory, market, or economic developments. FPA Funds and client accounts may purchase foreign securities, which are subject to interest rate, currency exchange rates, economic and political risks. The securities of smaller, less well-known companies can be more volatile than those of larger companies.
The return of principal in a bond fund or account is not guaranteed. Bond funds or accounts have the same issuer, interest rate, inflation, and credit risks that are associated with underlying bonds owned by the fund. Lower-rated bonds, convertible securities, and other types of debt obligations involve greater risks than higher-rated bonds.
Interest rate risk is when interest rates go up, the value of fixed income securities, such as bonds, typically go down and investors may lose principal value. Credit risk is the risk of loss of principal due to the issuer’s failure to repay a loan. Generally, the lower the quality rating of a security, the greater the risk that the issuer will fail to pay interest fully and return the principal in a timely manner. If an issuer defaults the security may lose some or all of its value. Convertible securities are generally not investment grade and are subject to greater credit risk than higher-rated investments. High-yield securities can be volatile and subject to much higher instances of default. High yield securities, senior loans, private placements, or restricted securities may carry liquidity risks.
The rating agencies that provide ratings are Standard and Poor’s, Moody’s, Fitch, DBRS, Kroll, and any other Nationally Recognized Statistical Ratings Organization (NRSRO). Credit ratings range from AAA (highest) to D (lowest). Bonds rated BBB or above are considered investment grade. Credit ratings BB and below are lower-rated securities (junk bonds). High-yielding, non-investment-grade bonds (junk bonds) involve higher risks than investment-grade bonds. Bonds with credit ratings of CCC or below have high default risk.
Value style investing presents the risk that the holdings or securities may never reach their full market value because the market fails to recognize what the portfolio management team considers the true business value or because the portfolio management team has misjudged those values. In addition, value style investing may fall out of favor and underperform growth or other styles of investing during given periods.
Portfolio composition will change due to active management. References to individual securities or sectors are for informational purposes only and should not be construed as recommendations by the Funds, FPA, the portfolio managers, or the distributor (as applicable). The portfolio holdings as of the most recent quarter-end may be obtained at https://fpa.com/resources/.
Please refer to the Fund’s prospectus for a complete overview of the Fund’s primary risks.
Glossary of Terms
ABS (Asset Backed Securities) are financial securities backed by a loan, lease or receivables against assets other than real estate and mortgage-backed securities.
Basis Point (bps) is equal to one hundredth of one percent, or 0.01%. 100 basis points = 1%.
Modified Duration (Duration) measures the change in the value of a bond in response to a change in 100-basis-point (1%) change in interest rates.
Nominal Treasury / Nominal Yield is the fixed interest rate that a bond promises to pay each year based on its face value.
Real yield is the rate of return on an investment after removing the effects of inflation.
Treasury Inflation-Protected Securities (TIPS) are U.S. government bonds designed to protect investors from inflation by adjusting their principal value and interest payments based on changes in the Consumer Price Index (CPI).
Category Definitions
Morningstar Short-Term Bond portfolios invest primarily in corporate and other investment-grade U.S. fixed-income issues and typically have durations of 1.0 to 3.5 years. These portfolios are attractive to fairly conservative investors, because they are less sensitive to interest rates than portfolios with longer durations. Morningstar calculates monthly breakpoints using the effective duration of the Morningstar Core Bond Index in determining duration assignment. Short-term is defined as 25% to 75% of the three-year average effective duration of the MCBI. As of June 30, 2026, there were 549 funds in this category.
The FPA Funds are distributed by Distribution Services, LLC, 190 Middle Street, Suite 301, Portland, ME 04101. Distribution Services, LLC and FPA are not affiliated.