You should consider the Fund’s investment objectives, risks, and charges and expenses carefully before you invest. The prospectus details the Fund’s objective and policies, charges, and other matters of interest to a prospective investor. Please read the prospectus carefully before investing. The prospectus may be obtained by visiting the website at fpa.com, by email at [email protected], toll-free by calling 1-800-982-4372, or by contacting the Fund in writing.
Average Annual Total Returns (%)
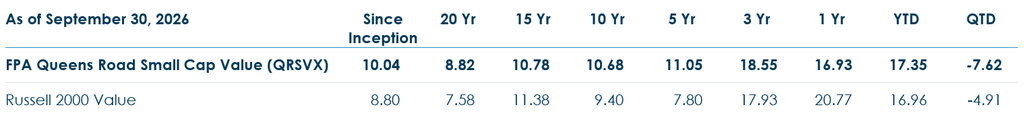
Index data source: Morningstar.
Past performance is no guarantee, nor is it indicative, of future results. Current performance may be higher or lower than the performance shown. This data represents past performance, and investors should understand that investment returns and principal values fluctuate, so that when you redeem your investment it may be worth more or less than its original cost. Current month-end performance data, which may be lower or higher than the performance data quoted, may be obtained at fpa.com or by calling toll-free, 1-800-982-4372. The Fund’s Total Annual Operating Expenses are 0.95% (Investor Class), 0.88% (Advisor Class), and 0.81% (Institutional Class).
The FPA Queens Road Small Cap Value Fund (“Fund”) commenced operations on June 13, 2002 (Inception date). Fund performance shown is for the Investor Class shares (QRSVX). Periods greater than one year are annualized. Fund performance is shown net of all fees and expenses and includes reinvestment of all distributions. Fund performance does not reflect the deduction of taxes that a shareholder would pay on Fund distributions or the redemption of Fund shares, which would lower these figures. An investor cannot invest directly in an index.
Prior to November 1, 2020, the performance shown reflects the historical performance of the Fund when Bragg Financial Advisors, Inc. (“BFA”) served as investment adviser of the Fund.
From inception of the Fund to December 31, 2004, BFA and its affiliates voluntarily absorbed certain expenses of the Fund and voluntarily waived its management fee. Had BFA not done this, returns would have been lower during that period. Effective January 1, 2005 through October 31, 2020, BFA charged a single unitary management fee and contractually agreed to pay all operating expenses of the Fund except for brokerage, taxes, interest, litigation expenses, and other extraordinary expenses. Prior to November 1, 2020, the Fund had a unitized fee structure that limited annual operating expenses to 1.18%.
Please see additional important disclosures at the end of this Commentary.
Dear Fellow Shareholder:
The FPA Queens Road Small Cap Value Fund (“Fund”) returned -7.62% in the third quarter of 2026 vs. -4.91% for the Russell 2000 Value Index (“R2KV”). Year to date, the Fund returned 17.35% vs. 16.96% for the R2KV. As a reminder, we expect to outperform in down markets and trail in speculative markets as a result of our diligent, disciplined, and patient process.
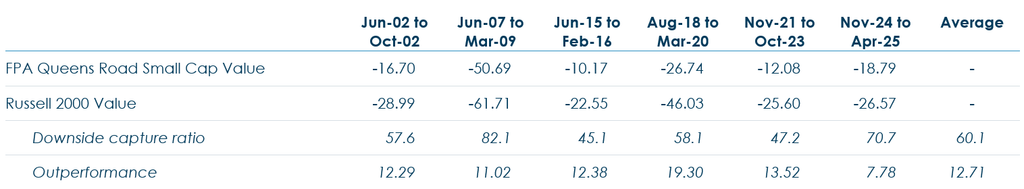
20% or Larger Russell 2000 Value Drawdowns Since Fund Inception (%)1
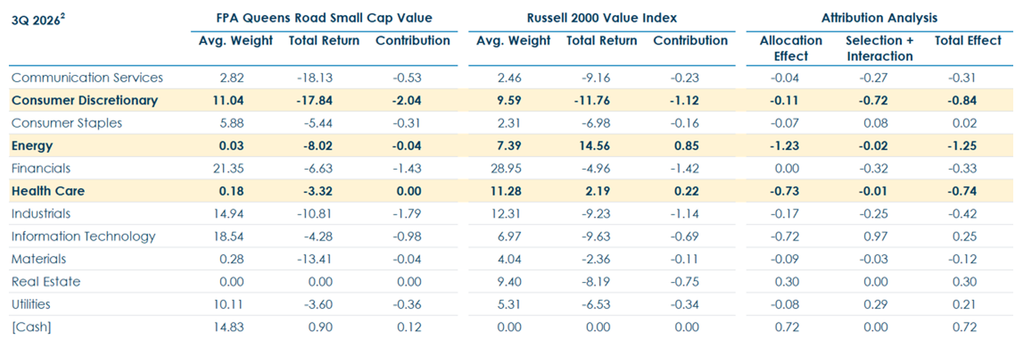
In a down quarter for the Russell 2000 Value Index, the Fund underperformed. All R2KV sectors were down except Energy and Healthcare (which is dominated by biotech). The bulk of our underperformance came from not owning companies in either sector (we did purchase small positions in a healthcare company and an energy services provider towards the end of the quarter). Our Consumer Discretionary picks, with a focus on apparel (PVH Corp, GIII and Levi’s) and auto (Dorman and Advance Auto Parts), also underperformed.
Quarterly results can be volatile, and we prefer that our investors look at performance over longer time periods – preferably a full market cycle. Over our history, the Fund has consistently trailed in up markets while also having lower downside participation. This year has been an anomaly – we outperformed in a strong and speculative market during the first half of the year (see our Q2 letter for details) and then gave some of that outperformance back in Q3. Nothing has changed in our process or the way that we invest. We believe that these recent results are a natural aberration in a market that currently favors speculation and story stocks over fundamentals. And believe that diligence, discipline, and patience will be rewarded in the end.
Market Commentary
We like to use this space to help our investors understand what we are seeing in the U.S. small-cap universe and how it relates to our investment process and portfolio activity. To that end, we would like to point our readers to a note published on September 8 by Dan Rasmussen and his team at Verdad Advisers.3 In it, Verdad provides some context on the recent outperformance of U.S. small cap.
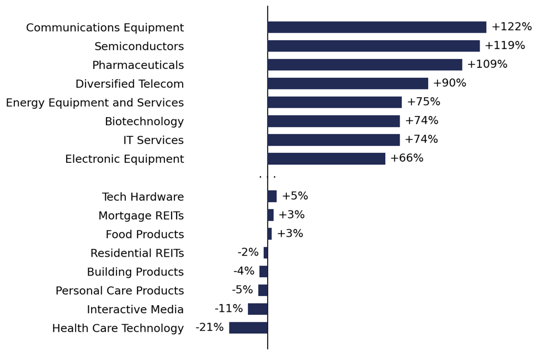
Over the last twelve months (to Verdad’s publication date), small-cap outperformance has been driven by more speculative segments of the market, including loss-making companies, biotech and story stocks. Verdad’s conclusion is “The past year’s small-cap rally was real, but it was not the revaluation small-cap investors have been waiting two decades for. It was a lottery drawing.” We are pleased with our performance in an environment where the normal, boring companies that we prefer have been out of favor.
Figure 3: LTM Small-Cap Segmentation Performance4
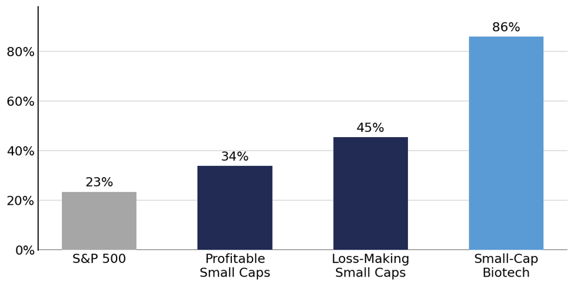
Figure 4: LTM Small-Cap Industry Winners and Losers5
In previous letters, we have shown that small, high-quality stocks are trading at very reasonable valuations (see our 4Q 2025 letter for example).6 Verdad comes to the same conclusion and shows that profitable small caps are trading at a distinct valuation advantage to their larger peers.
Figure 7: EV/EBITDA of Small Caps vs. Large Caps7
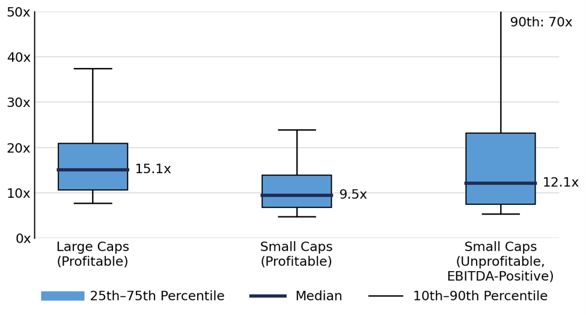
Verdad’s further concern is the high valuation multiples paid for small companies by U.S. private equity firms – 17x EV/EBITDA and 12x EV/adj. EBITDA.8 While investors clamor for allocations to private equity, profitable small companies of similar quality are available in the public markets at a fraction of the valuation. We couldn’t agree more. The market overall is showing signs of froth and excess, but we are finding a diversity of quality companies to invest in at very reasonable, though not dirt cheap, valuations.
Portfolio Commentary
In Q3, we continued to reduce our holdings in highly appreciated technology stocks and invest the proceeds in a diversity of high-quality small businesses. We have always had a preference for “boring” businesses that do a good job providing key goods and services. These types of companies lack flash and hype but also tend to avoid frequent and disruptive innovation cycles. We suspect that the companies we bought were available at attractive prices because they were overlooked by a market that seems to be singularly focused on the “AI trade” and its derivatives.
For the quarter, we added five new positions – Hayward Holdings (HAYW), Teleflex (TFX), Simpson Manufacturing (SSD), FTI Consulting (FCN), and Flowco (FLOC). There were no other significant additions to the portfolio.9
Hayward Holdings (HAYW) manufactures swimming pool equipment such as pumps, heaters, and filters, primarily for residential pools and primarily in the U.S. Hayward benefits from an oligopolistic industry structure and a sales mix weighted towards replacement and remodeling, which have allowed for significant pricing power over time. The industry is still normalizing from the excess demand seen during Covid. The low level of new pool construction is expected to slow further with higher interest rates and slowing existing home sales. These worries allowed us to purchase shares at the attractive price of 15x this year’s earnings.
Teleflex (TFX) manufactures a portfolio of medical consumables – mostly a range of catheters along with other surgical devices. The company’s recent history has been dramatic – previous management ran a failed growth playbook across unrelated urology products that left the company over levered and unfocused. But we are investing following a strategic and financial turnaround where the company sold its unrelated businesses, is using the proceeds to de-lever and brought in Jason Weidman from Medtronic as CEO. Near-term financials have several moving parts, but we think we are paying a low double digit multiple of normal earnings for a strong and refocused medical device portfolio.
Simpson Manufacturing (SSD) has a dominant position selling trusses, connectors, fasteners, anchors, and other products used in residential housing construction. The company has an exceptional history of market share gains while extending its franchise into new products and geographies.
FTI Consulting (FCN) is a very high value add consultant. Most of the earnings come from its core franchises in turnaround and restructuring (Corpfin) and forensic and litigation (FLC). We believe these businesses should be contra-cyclical and relatively immune from AI disruption. We think CEO Steve Gunby has done a phenomenal job growing the company and allocating capital over his 12-year tenure. Now, the company is aggressively buying back stock that sold off because of short-term earnings volatility. We were happy to buy a starting position at roughly 15x this year’s earnings.
Flowco (FLOC) manufactures, sells, and rents differentiated gas lift and vapor recovery equipment to the U.S. onshore oil and gas industry. The company is tied to ongoing production rather than new wells and should benefit from inflecting rig counts in the Permian. Flowco has strong growth and returns on capital, and we were comfortable initiating an underweight position at a low double digit multiple of this year’s earnings.
We sold our small position in Everus Construction (ECG). Everus, a spin-off from portfolio holding MDU, is an electrical contractor that benefited from growing utility and data center work and had gotten expensive.
We significantly reduced our holdings in Ducommun (DCO), Vishay Intertechnology (VSH), and Littelfuse (LFUS). Ducommun makes structural and electronic systems for military and commercial planes. The company has executed well but has gotten expensive. Vishay and Littelfuse make electrical components with broad end markets, including data centers. These companies are benefiting from cyclical tailwinds and have similarly gotten expensive. We made additional reductions to our technology holdings TD Synnex (SNX), Arrow Electronics (ARW), and Synaptics (SYNA) for similar reasons.
At quarter end, our cash position was 10.3%.10
Trailing Twelve-Month Top and Bottom Contributors (%)11
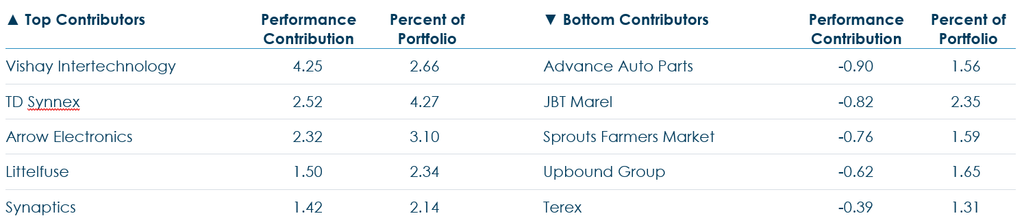
Top Contributors
- Vishay Intertechnology (VSH) makes passive electronic components and discrete semiconductors (resistors, inductors, capacitors, MOSFETs, diodes, etc.). Although the industry is cyclical, competitive dynamics are stable and VSH benefits from incremental growth from electric vehicles and industrial electrification. In 2025, the industry was struggling from a cyclical downturn following the excesses and component hoarding of the Covid era. The stock declined again when President Trump announced his tariffs in April 2025. But the industry has come roaring back; the stock rallied aggressively following VSH’s Q1 earnings release announced a year-over-year sales increase of 17%, strength across all end markets and distribution channels, and a book-to-bill ratio of 1.34.12 Vishay is also incrementally selling to data centers. We believe the stock may have gotten caught up in the “AI trade” and have aggressively reduced our position.
- TD Synnex (SNX) is the largest IT distributor globally. The company has done a good job diversifying away from its historical position in hardware (PCs, peripherals, servers, networking equipment, etc.) and into software, security, and services. TD Synnex is modestly levered and uses its cash flow to repurchase shares and pay dividends. On March 31, the company reported blow-out earnings and provided financials for Hyve, its data center business.13 Hyve is growing billings at a nearly 100% annualized rate and is on track to contribute 1/3 of the company’s operating earnings this year. These numbers were higher than investors anticipated, and the stock has performed very well since their release. We think that TD Synnex is exceptionally well run, has scale and scope advantages versus smaller competitors, and that profits will continue to grow with IT spending at a GDP+ rate. We have trimmed our position, but SNX trades at roughly 13x this year’s earnings and continues to be a top 5 holding for the Fund.
- Arrow Electronics (ARW) distributes a broad array of semiconductors. Arrow is larger with better financials than its closest competitor Avnet (AVT), and these companies produce a lot of cash despite some cyclicality. Arrow used its strong cash flows during the Covid component shortages (2020 through 2023) to retire roughly one-third of its outstanding shares. A year ago, Arrow was suffering from a cyclical trough and the Trump tariffs. But the industry has come roaring back and in its Q1 earnings release on May 7, ARW reported 39% YoY earnings growth and more than doubled its adjusted EPS.14 We have been trimming our position, but the stock trades at ~11x this year’s earnings and we still hold a substantial position.
- Littelfuse (LFUS) manufactures niche electrical components including fuses, sensors, passives, and semiconductors that are sold into a broad array of end markets. The company is very well run and mid-single digit organic growth is supplemented by tuck-in acquisitions. Operating margins are in the high teens and returns on capital are strong. We significantly added to our position in April 2025 when the stock declined on tariff fears. Since then, LFUS’s share price has more than doubled as the company demonstrated it could navigate tariffs, sales and orders accelerated out of their post-Covid trough, and the company recorded incremental sales into data centers.
- Synaptics (SYNA) has a legacy business of designing chips that power touch controls and haptics for consumer electronics. But starting in 2020, the company began developing Astra – an integrated sensing, processing, and communication solution to enable the industrial internet or internet of things (IoT). It turns out that Astra has an additional application in running AI processing on the edge – a function that was validated when Synaptics signed an extensive collaboration and co-development deal with Google Labs in 2025. On June 25, Synaptics agreed to be acquired by On Semi (ON) in an all stocks deal worth $7B.15
Bottom Contributors
- Advance Auto Parts (AAP) is an auto parts distributor that sells to both professional repair technicians and retail customers. The company is struggling through a difficult turnaround but is starting to show green shoots. The balance sheet is in good shape, new management has articulated a credible restructuring plan, and the company’s operating margins are starting to creep upward. Results have been inconsistent as management works through the restructuring of Advance Auto’s distribution, inventory, merchandising, and store operations. Shares sold off on August 20 when AAP released Q2 results that missed investor expectations.16
- JBT Marel (JBTM) makes food processing equipment. Half the business is protein, concentrated in chicken, while half the business is processed food and beverages. Half of sales come from aftermarket parts and service, food markets are relatively non-cyclical, and the company has a history of consistent margin improvements. Shares have been weak as investors worry about profitability at JBTM’s protein customers and the company missed Q2 earnings on August 3. We have been pleased to add shares at less than 15 times this year’s earnings.17
- Sprouts Farmers Market (SFM) is a supermarket chain focusing on fresh, natural, and organic products. The company has strong operating margins, attractive returns on capital, and excellent new store economics. Through April 2025, SFM’s stock performed extremely well in concert with strong revenue growth and rising earnings estimates. As SFM’s valuation increased, we trimmed our position in late 2024 and early 2025. Then, when growth slowed in the second half of 2025, SFM’s share price collapsed. Today, SFM trades at a low-teens multiple of forward earnings and we are comfortable holding a mid-sized position.
- Upbound Group (UPBD) lends to sub-prime consumers in two primary segments: Rent-a-Center, which focuses on furniture and appliances through physical stores; and Acima, which offers last-look financing through associated retailers including electronics and tire shops. Sub-prime consumers are struggling, but Upbound’s operating results have held up. The company has been slow to de-lever after purchasing Acima in 2021. Shares are cheap, but we have been slow to add given the company’s leverage and questions about its business model.
- Terex (TEX) is a specialty vehicle manufacturer that makes fire trucks and ambulances, waste and recycling trucks, materials processing equipment, utility trucks, and aerials. We acquired shares when the company acquired Fund holding Rev Group (REVG) in a stock and cash deal. CEO Simon Meester has done a good job upgrading the portfolio and the company is currently in the process of selling its more cyclical aerials business. We think shares are attractively priced at roughly 11x this year’s earnings.
Conclusion
While we cannot control short-term volatility, we remain firmly focused on the long-term fundamental performance of our investments. We never predict market direction, but we feel good about the Fund’s long-term prospects. We will continue to manage our portfolio with diligence, discipline, and patience.
As always, and as significant co-investors in the Fund, we appreciate your trust in us to be good stewards of your capital. Please let us know if you would like to discuss our performance or portfolio holdings in greater detail.
Respectfully,
Steve Scruggs, CFA, Portfolio Manager
Ben Mellman, Portfolio Manager
October 12, 2026
1 As of September 30, 2026. Source: Morningstar Direct, FPA. Data shown for the FPA Queens Road Small Cap Value Fund – Investor Class (“Fund”). Inception of the Fund was June 13, 2002. The periods referenced above reflect Russell 2000 Value drawdowns 20% or greater and are calculated from that index’s peak and trough dates, (i.e., 6/28/2002-10/9/2002, 6/4/2007-3/9/2009, 6/23/2015-2/11/2016, 8/22/2018-3/23/2020, 11/8/2021-10/27/2023, 11/25/2024-4/8/2025). Please see page 1 for net performance of the Fund since inception. Please also see the end of this commentary for Important Disclosures and Definitions of Key Terms.
2 Attribution data is preliminary. Attribution analysis is generated utilizing FactSet and is presented gross of investment management fees, transactions costs, and Fund operating expenses, which if included, would reduce the returns presented. Past performance is no guarantee of future results. Performance results can vary slightly from those reported by our administrator. Totals may not sum due to rounding.
3 Source: Verdad Advisers, “Small Caps 2026: The Lottery and the Leftovers”; https://mailchi.mp/verdadcap/small-caps-2026-the-lottery-and-the-leftovers?e=f7930ade53.
4 Attributed to Capital IQ, Verdad analysis.
5 Attributed to Capital IQ, Verdad analysis.
6 https://fpa.com/fpa-queens-road-small-cap-value-fund-4q25-commentary/.
7 Attributed to Capital IQ, Verdad analysis.
8 Attributed to S&P Capital IQ, PitchBook, Verdad analysis.
9 We define a significant addition as increasing our holdings by 33% or more in positions where we have a portfolio weight of at least 1% at the previous quarter end.
10 Cash includes an investment in a short-term treasury ETF.
11 Reflects the top contributors and top detractors to the Fund’s performance based on preliminary contribution to return for the trailing twelve months (TTM) period ending September 30, 2026. Contribution is presented gross of investment management fees, transactions costs, and Fund operating expenses, which if included, would reduce the returns presented. Portfolio weights represent the average weights over the periods noted. A copy of the methodology used and a list of every holding’s contribution to the overall Fund’s performance during the TTM is available by contacting [email protected]. It should not be assumed that recommendations made in the future will be profitable or will equal the performance of the securities listed. Totals may not sum due to rounding. Note: September 30, 2026 company descriptions were developed by the investment team and unless otherwise noted reflect the most recent data made available by the companies or third-party research firms the investment team believe to be reliable.
12 Source: https://ir.vishay.com/financial-information/quarterly-results.
13 Source: https://ir.tdsynnex.com/financials/quarterly-results/default.aspx.
14 Source: https://investor.arrow.com/investors/default.aspx.
15 Source: https://www.synaptics.com/company/news/onsemi-to-acquire-synaptics-to-enable-the-next-generation-of-intelligent-systems-for-physical-ai.
16 Source: https://ir.advanceautoparts.com/investors/news-and-events/events-and-presentations/default.aspx.
17 Source: http://ir.jbtmarel.com/news/press-releases/detail/540/jbt-marel-corporation-reports-second-quarter-2026-results.
Important Information
This Commentary is for informational and discussion purposes only and does not constitute, and should not be construed as, an offer or solicitation for the purchase or sale of any securities, products or services discussed, and neither does it provide investment advice. Any such offer or solicitation shall only be made pursuant to the Fund’s prospectus, which supersedes the information contained herein in its entirety. This Commentary does not constitute an investment management agreement or offering circular.
The statements contained herein reflect the opinions and views of the portfolio managers as of the date written, are subject to change without notice, and may be forward-looking and/or based on current expectations, projections, and/or information currently available. Such information may not be accurate over the long term. These views may differ from other portfolio managers and analysts of the firm as a whole and are not intended to be a forecast of future events, a guarantee of future results or investment advice.
Portfolio composition will change due to ongoing management of the Fund. References to individual securities or sectors are for informational purposes only and should not be construed as recommendations by the Fund, the portfolio manager, the Adviser, the Sub-Adviser or the distributor. It should not be assumed that future investments will be profitable or will equal the performance of the security or sector examples discussed. The portfolio holdings as of the most recent quarter-end may be obtained at fpa.com.
Future events or results may vary significantly from those expressed and are subject to change at any time in response to changing circumstances and industry developments. The information and data contained herein have been prepared from sources believed reliable, but the accuracy and completeness of the information cannot be guaranteed and is not a complete summary or statement of all available data.
The information contained herein is not complete, may change, and is subject to, and is qualified in its entirety by, the more complete disclosures, risk factors, and other information contained in the Fund’s prospectus and Statement of Additional Information. The information is furnished as of the date shown. No representation is made with respect to its completeness or timeliness. The information is not intended to be, nor shall it be construed as, investment advice or a recommendation of any kind.
Certain statements contained in this presentation may be forward-looking and/or based on current expectations, projections, and information currently available. Actual events or results may differ materially from those we anticipate, or the actual performance of any investments described herein may differ from those reflected or contemplated in such forward-looking statements, due to various risks and uncertainties. We cannot assure future results and disclaim any obligation to update or alter any forward-looking statements, whether as a result of new information, future events, or otherwise. Such statements may or may not be accurate over the long term. Statistical data or references thereto were taken from sources which we deem to be reliable, but their accuracy cannot be guaranteed.
The reader is advised that the Fund’s investment strategy includes active management with corresponding changes in allocations from one period of time to the next. Therefore, any data with respect to investment allocations as of a given date is of limited use and may not be reflective of the portfolio manager’s more general views with respect to proper geographic, instrument and/or sector allocations. The data is presented for indicative purposes only and, as a result, may not be relied upon for any purposes whatsoever.
In making any investment decision, you must rely on your own examination of the Fund, including the risks involved in an investment. Investments mentioned herein may not be suitable for all recipients and in each case, potential investors are advised not to make any investment decision unless they have taken independent advice from an appropriately authorized advisor. An investment in any security mentioned herein does not guarantee a positive return as securities are subject to market risks, including the potential loss of principal. You should not construe the contents of this document as legal, tax, investment or other advice or recommendations.
Fund performance presented is calculated on a total return basis, which includes the reinvestment of all income, plus realized and unrealized gains/losses, if applicable. Unless otherwise indicated, performance results are presented on a net of fees basis and reflect the deduction of, among other things: management fees, brokerage commissions, operating and administrative expenses, and accrued performance fee/allocation, if applicable.
The information provided in this presentation is based upon data existing as of the date(s) of the report and has not been audited or reviewed. While we believe the information to be accurate, it is subject in all respects to adjustments that may be made after proper review and reconciliation.
Investments carry risks and investors may lose principal value. Capital markets are volatile and can decline significantly in response to adverse issuer, political, regulatory, market, or economic developments. Securities of smaller, less well-known companies involve greater risks, and they can fluctuate in price more than larger company securities. You risk paying more for a security than you received from its sale.
The Fund primarily invests in equity securities (common stocks, preferred stocks and convertible securities) of small-capitalization U.S. companies, defined as those with market-capitalization, at the time of purchase, that is no greater than the largest market-capitalization of any company included in the Russell 2000 Index. Investing in small companies involves special risks including, but not limited to, the following: smaller companies typically have more risk and their company stock prices are more volatile than that of large companies; their securities may be less liquid and may be thinly traded which makes it more difficult to dispose of them at prevailing market prices; these companies may be more adversely affected by poor economic or market conditions; they may have limited product lines, limited access to financial resources, and may be dependent on a limited management group; and small-cap stocks may fluctuate independently of large-cap stocks. All investment decisions are made at the discretion of the Portfolio Manager, in accordance with the then-current prospectus. Comparison to any index is for illustrative purposes only.
The prices of securities held by the Fund may decline in response to certain events taking place around the world, including those directly involving the companies whose securities are owned by the Fund. Securities in the Fund’s portfolio may underperform due to inflation (or expectations for inflation), interest rates, global demand for particular products or resources, natural disasters, pandemics, epidemics, terrorism, regulatory events and governmental or quasi-governmental actions. There is a risk that you may lose money by investing in the Fund.
Value style investing presents the risk that the holdings or securities may never reach their full market value because the market fails to recognize what the portfolio management team considers the true business value or because the portfolio management team has misjudged those values. In addition, value style investing may fall out of favor and underperform growth or other styles of investing during given periods.
Please refer to the Fund’s prospectus for a complete overview of the primary risks associated with the Fund.
©2026 Morningstar, Inc. All Rights Reserved. The Morningstar information contained herein: (1) is proprietary to Morningstar and/or its content providers; (2) may not be copied or distributed; and (3) is not warranted by Morningstar to be accurate, complete, or timely. Neither Morningstar nor its content providers are responsible for any damages or losses arising from any use of this information. Past performance is no guarantee of future results.
The FPA Funds are distributed by Distribution Services, LLC. Distribution Services, LLC and FPA are not affiliated.
Index Definitions
Comparison to any index or benchmark is for illustrative purposes only and should not be relied upon as a fully accurate measure of comparison. The Fund may be less diversified than the indices noted herein and may hold non-index securities or securities that are not comparable to those contained in an index. Indices will hold positions that are not within the Fund’s investment strategy. Indices are unmanaged and do not reflect any commissions, transaction costs, or fees and expenses which would be incurred by an investor purchasing the underlying securities and which would reduce the performance in an actual account. You cannot invest directly in an index.
The Russell 2000 Index measures the performance of the small-cap segment of the U.S. equity universe. It is a market cap weighted index that includes the smallest 2,000 companies covered in the Russell 3000 universe of United States-based listed equities.
The Russell 2000 Value Index measures the performance of the small-cap value segment of the U.S. equity universe. It includes those Russell 2000 companies that are considered more value-oriented relative to the overall market as defined by Russell’s leading style methodology.
Small-cap Value Companies: The term small-cap describes companies with a relatively small market-capitalization. A company’s market-capitalization is the market value of its outstanding shares. The definition for small-cap varies but generally means a company with $300 million to $2 billion in market-capitalization.
Glossary of Terms
Allocation Effect quantifies the value added or lost by a portfolio manager’s macro decision to overweight or underweight specific sectors, industries, or asset classes relative to a benchmark.
Book-to-Bill Ratio is the ratio of a company’s orders to its revenue. Book-to-bill can provide an indication of future revenue trends as orders are expected to translate into revenue with a consistent cadence.
Contribution to Return (CTR) measures how much a specific asset, sector, or security adds to the total return of a portfolio over a given period.
Downside capture ratio is used to evaluate how well an investment manager performed relative to an index during periods when that index has fallen. The ratio is calculated by dividing the manager’s returns by the returns of the index during the down market and multiplying that factor by 100. BPS or basis points; 1 bps is equal to 0.01%.
Earnings per share (EPS) is calculated as a company’s profit divided by the outstanding shares of its common stock.
Expected earnings are an estimate for a company’s future quarterly or annual earnings per share (EPS).
Forward earnings are an estimate of the next period’s earnings of a company, usually through the completion of the current fiscal year and sometimes to the following fiscal year.
Market Cycle Performance is defined as a period that contains a decline of at least 20% from the previous market peak over at least a two-month period and a rebound to establish a new peak above the prior market peak.
Selection Effect and the Interaction Effect isolate the impact of picking individual securities and how those stock-picking choices combine with active asset weights.
Total Effect represents the total value added or lost by a portfolio manager’s active decisions relative to the benchmark.