You should consider the Fund’s investment objectives, risks, and charges and expenses carefully before you invest. You can obtain additional information by visiting the website at https://fpa.com/fund/source-capital/, by email at [email protected], or toll-free by calling 1-800-279-1241.
Average Annual Total Returns (%)
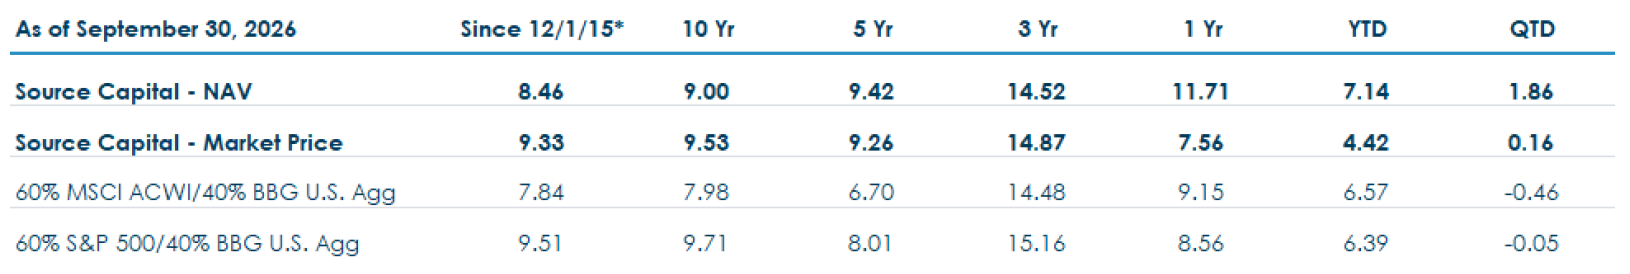
Index data source: Morningstar.
Past performance is no guarantee of future results and current performance may be higher or lower than the performance shown. This data represents past performance and investors should understand that investment returns and principal values fluctuate, so that when you redeem your investment it may be worth more or less than its original cost. Current month-end performance data, which may be lower or higher than the performance data quoted, may be obtained at fpa.com or by calling toll-free, 1-800-982-4372.
Periods over one year are annualized. Fund performance is shown net of all fees and expenses and includes the reinvestment of distributions. Returns do not reflect the deduction of taxes that a shareholder would pay on Fund distributions, which would lower these figures. Since Source Capital is a closed-end investment company and its shares are bought and sold on the New York Stock Exchange, your performance may also vary based upon the market price of the common stock. Comparison to any index is for illustrative purposes only. An investor cannot invest directly in an index. The Fund does not include outperformance of any index or benchmark in its investment objectives.
* On December 1, 2015, the Fund transitioned to a balanced strategy and the current portfolio managers assumed management of the Fund on that date.
Please see important disclosures at the end of this commentary.
Dear Shareholder:
Performance Overview
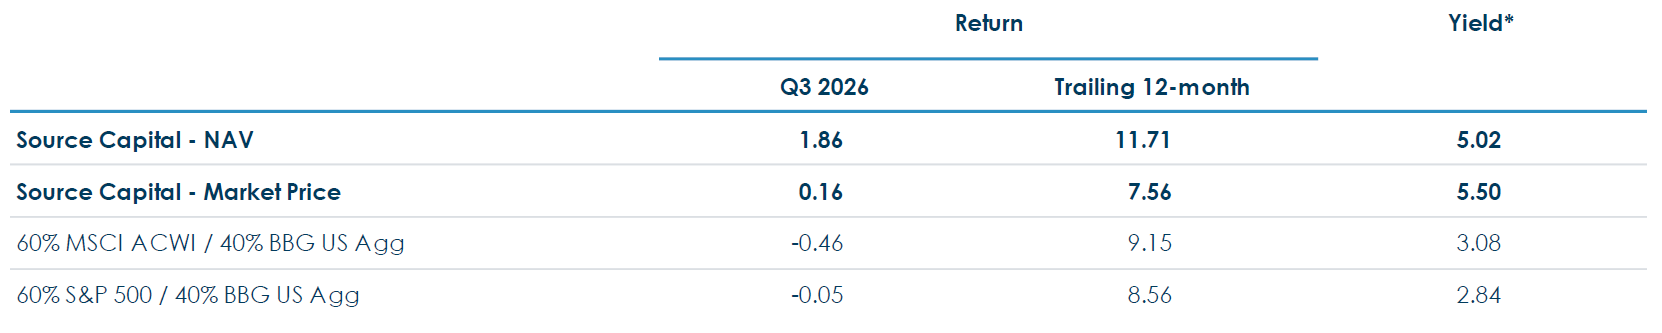
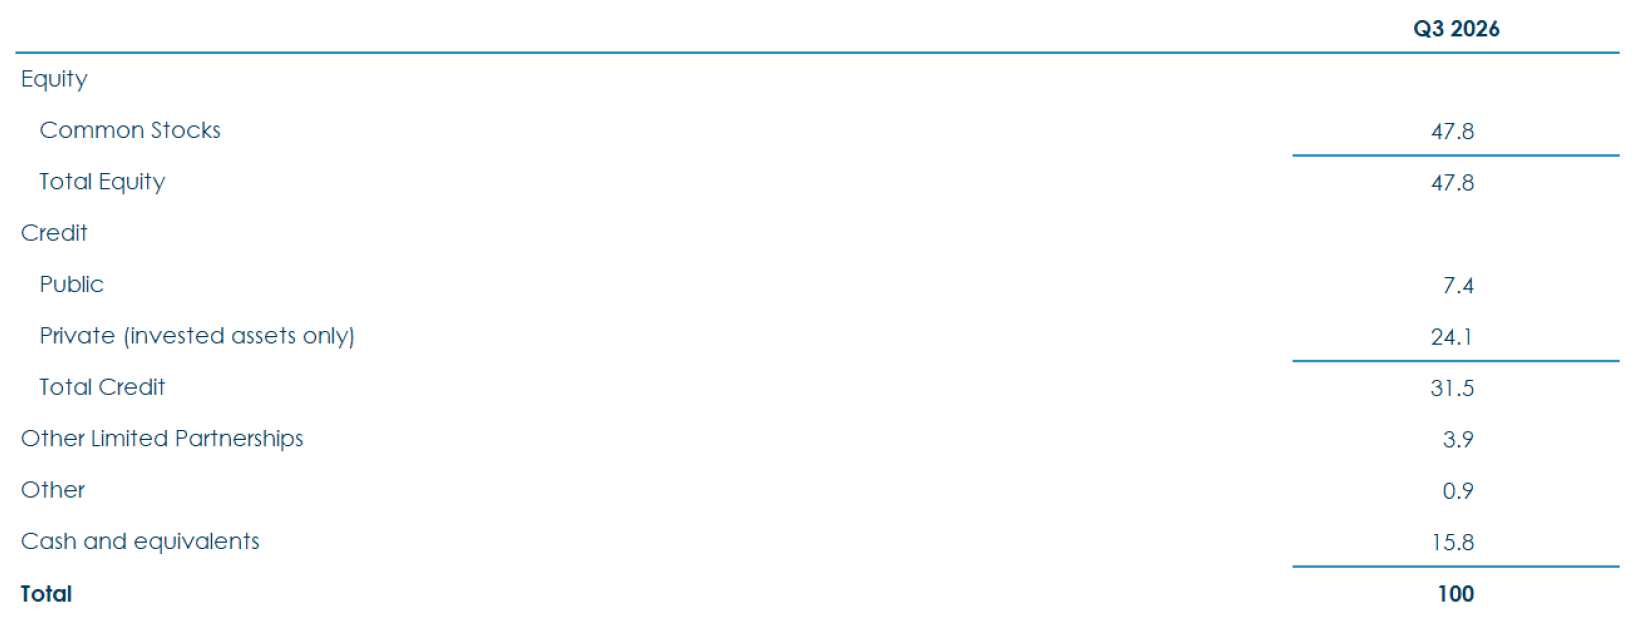
Source Capital’s (“Source” or “Fund”) net asset value (NAV) gained 1.86% for the quarter and 11.71% for the trailing twelve months. It captured 128.0% of the return of the balanced MSCI ACWI/Bloomberg US Agg index, the Fund’s primary illustrative benchmark, over the trailing twelve months. The Fund’s risk exposure is nearly balanced between Equities and Credit.
Performance versus Illustrative Indices (%)1
Portfolio Exposure (%)2
Third-quarter activity largely continued the events discussed in the first-half commentary. In addition to trimming positions that have benefited from their association with the AI ecosystem, we added new names in healthcare (i.e., Boston Scientific, HCA) as well as SMIDs both domestically and abroad (i.e., Core & Main and JBT Marel).
Turning to our cash position, a rising rate environment has offered the opportunity to buy short-term treasuries with yields close to 5% if one takes some liberties with rounding. In addition to taking advantage of these opportunities, the Fund has also initiated a position in Treasury Inflation-Protected Securities (TIPS), with real yields north of 3%.
Moving to corporates, spreads remain relatively tight versus Treasuries, however, given the speed at which rates have recently risen, we would be surprised if this does not cause stress somewhere in the credit market. Rest assured, consistent with prior behavior, we will run our ruler over such opportunities if they present themselves.
Portfolio Discussion3
Equity
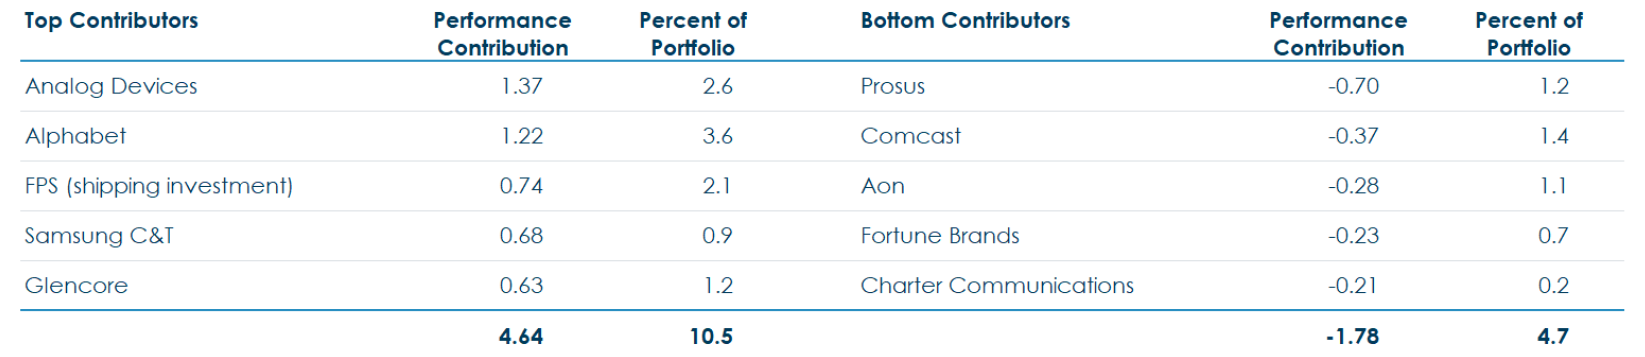
In the Fund’s recent performance, over the previous twelve months, Source’s top five equity performers contributed 4.64% to its return, while its bottom five contributed -1.78%.
Trailing Twelve-Month Top and Bottom Contributors (%) as of September 30, 20264
The following companies impacted portfolio performance but have not been recently discussed.5
Analog Devices, a leading supplier of analog and mixed-signal semiconductors, continued to benefit from strong demand tied to AI infrastructure, industrial applications, and communications. During the quarter, ADI reported record revenue of $4.0bn, with year-over-year growth led by its data center and industrial businesses; while management noted strengthening demand across its portfolio and provided a strong revenue outlook for the following quarter. ADI’s broad end-market exposure, coupled with rising semiconductor content tied to AI infrastructure, has helped accelerate growth as the broader analog semiconductor cycle has recovered.
Alphabet benefited from continued strength across its core businesses and increasing investor confidence in its AI positioning. Search remained resilient despite concerns that generative AI could disrupt traditional search behavior, while Google Cloud continued to benefit from growing demand for AI infrastructure. The company has continued to integrate AI functionality throughout its products, while its collection of other assets, including YouTube and Waymo, provides additional sources of long-term value.
Samsung C&T benefited from improving investor recognition of the value embedded in its portfolio of strategic holdings, including its exposure to the broader Samsung ecosystem, alongside improving results in its operating businesses. Its construction business benefited from demand for high-tech facilities, while the company also maintains exposure to biotechnology, energy and other businesses. The shares appreciated despite volatility during the period as investors increasingly focused on the company’s underlying asset value and opportunities across its collection of businesses.
Although Prosus’ operating results continued to improve, including greater profitability across its e-commerce businesses and improving cash generation, the shares declined as investors weighed execution risk associated with the company’s acquisitions and investments. Prosus also continued its open-ended share repurchase program, supported in part by sales of Tencent shares, and it has historically been attractive given the discount between Prosus’ share price and its underlying net asset value.
Charter Communications and Liberty Broadband detracted from performance amid continued competitive pressure within the U.S. broadband market. Charter has faced competition from fiber overbuilders and fixed wireless offerings, while elevated capital expenditures and financial leverage have contributed to share volatility. During the quarter, Charter completed its acquisition of Liberty Broadband and Cox Communications, improving the company’s balance sheet and expanding geographic coverage. We continue to view Charter’s combination of fixed broadband and mobile connectivity as an important competitive offering as the company works through the industry’s changing competitive environment.
Fixed Income
Traditional
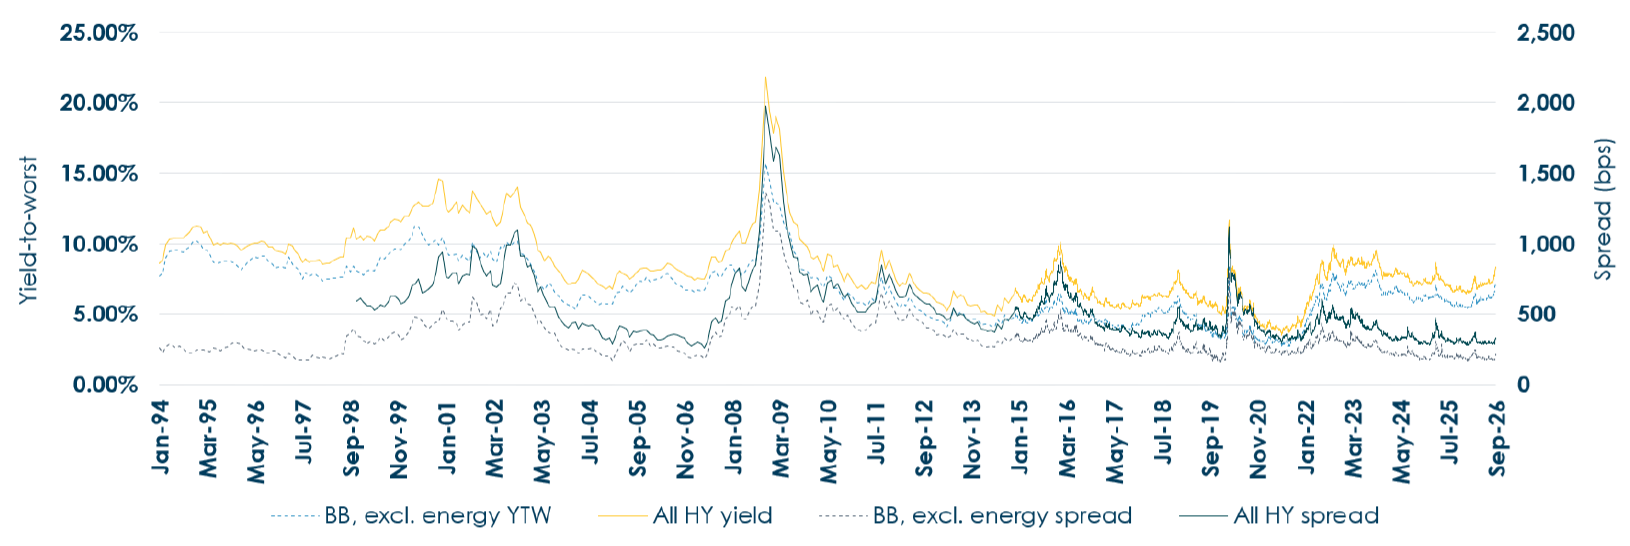
High-yield spreads widened during the quarter, led by a larger spread in the lowest-rated debt. As an indicator of the core of the high yield market, spreads on BB-rated debt, excluding energy increased from historically low levels at the end of the second quarter but remain relatively low by historical standards.
Bloomberg U.S. Corporate High-Yield and BB ex. Energy Index Yield-To-Worst (YTW) and Spread6

Private Credit
Source’s exposure to private credit increased to 24.1% at quarter-end (29.2% committed, including called and uncalled capital), up 3.1% from the prior quarter. We aim to continue increasing that exposure over time.
Corporate & Other
Distribution
On July 21, 2026, the Fund’s Board approved maintaining the current rate of 20.83 cents per share for its regular monthly distribution through November 2026.7 This equates to an annualized unlevered distribution rate of 5.50% based on the Fund’s closing market price on September 30, 2026.
Discount to NAV
The Fund’s discount to NAV closed at 8.78% at quarter-end. The average discount to NAV for the trailing twelve months was 5.43%.8
Closing
As always, we remain patient but prepared to act when opportunities present themselves. We are currently building positions in several new investments that we believe may offer attractive long-term return potential at sensible valuations, and we look forward to sharing more in our year-end letter.
Respectfully submitted,
Source Capital Portfolio Managers
November 5, 2026
¹ Comparison to the indices is for illustrative purposes only. An investor cannot invest directly in an index. Fund shareholders may only invest or redeem their shares at market value (NYSE: SOR), which may be higher or lower than the Fund’s net asset value (NAV).
* Source: FPA, FactSet, Bloomberg. As of September 30, 2026. The “yield” shown for the Fund is the NAV distribution yield (also referred to as the Fund’s “distribution rate” as a % of NAV) and the Fund’s Market Price distribution yield (as a % of market price). Dividend yield is used for the MSCI ACWI and the S&P 500. Yield to Worst is used for the Bloomberg US Agg. Please refer to the Important Disclosures for definitions of the different measures of yield used in this table. For more information related to the Fund’s distribution rate, please see https://fpa.com/fund/source-capital/. Dividends and other distributions are not guaranteed.
² Source: FPA, as of September 30, 2026. Portfolio composition will change due to ongoing management of the Fund. Cash includes the non-invested portion of private credit investments. Totals may not add up to 100% due to rounding.
3 References to individual securities are for informational purposes only, are subject to change, and should not be construed as a recommendation or a solicitation to buy or sell a particular security. Portfolio composition will change due to ongoing management of the Fund. Portfolio holdings for the Fund can be found at fpa.com.
4 Reflects the top five contributors and detractors to the Fund’s performance based on contribution to return for the trailing twelve months (“TTM”). Contribution is presented gross of investment management fees, transactions costs, and Fund operating expenses, which if included, would reduce the returns presented. Percent of portfolio reflects the average position size over the period. The information provided does not reflect all positions purchased, sold or recommended by FPA during the quarter. A copy of the methodology used and a list of every holding’s contribution to the overall Fund’s performance during the TTM is available by contacting FPA Client Service at [email protected]. It should not be assumed that recommendations made in the future will be profitable or will equal the performance of the securities listed. Totals might not add up due to rounding.
5 Historical commentaries for the Fund can be accessed on the website at https://fpa.com/insights/. The company data and statistics referenced in this section, including competitor data, are sourced from company press releases, investor presentations, financial disclosures, SEC filings, or company websites, unless otherwise noted.
6 Source: Bloomberg. As of September 30, 2026. YTW is Yield-to-Worst. Spread reflects the quoted spread of a bond that is relative to the security off which it is priced, typically an on-the-run Treasury. For illustrative purposes only. A percentile is a statistical measure that indicates the value below which a given percentage of observations in a group of data falls.
7 For more information related to the Fund’s distribution rate, please see https://fpa.com/insights/?category_name=fund-announcements. Dividends and other distributions are not guaranteed.
8 Source: FPA. The average is calculated using daily discount rates.
Past performance is no guarantee, nor is it indicative, of future results.
Important Information
This Commentary is for informational and discussion purposes only and does not constitute, and should not be construed as, an offer or solicitation for the purchase or sale with respect to any securities, products or services discussed, and neither does it provide investment advice. This Commentary does not constitute an investment management agreement or offering circular.
Current performance information is updated monthly and is available by calling 1-800-982-4372 or by visiting fpa.com. Performance data quoted represents past performance, which is no guarantee of future results. Current performance may vary from the performance quoted. The returns shown for Source Capital are calculated at net asset value per share, including reinvestment of all distributions. Returns do not reflect the deduction of taxes that a shareholder would pay on Fund distributions, which would lower these figures. Since Source Capital is a closed-end investment company and its shares are bought and sold on the New York Stock Exchange, your performance may also vary based upon the market price of the common stock.
The Fund is managed according to its investment strategy which may differ significantly in terms of security holdings, industry weightings, and asset allocation from those of the comparative indices. Overall Fund performance, characteristics and volatility may differ from the comparative indices shown.
There is no guarantee the Fund’s investment objectives will be achieved. You should consider the Fund’s investment objectives, risks, and charges and expenses carefully before you invest. You can obtain additional information by visiting the website at https://fpa.com/fund/source-capital/, by email at [email protected], or toll-free by calling 1-800-279-1241.
Effective January 1, 2025, Source Capital, Inc. was reorganized into a Delaware Trust. The Fund’s new name is Source Capital, but it continues to trade on the NYSE under the SOR ticker. There was no change in its investment objective, investment strategy, or fundamental investment policies. FPA continues to be the adviser to the Fund.
The views expressed herein and any forward-looking statements are highly speculative, current only as of the date of this publication and are those of the portfolio management team. Forward-looking statements can be identified by the use of terms such as “may”, “will”, “should”, “expect”, “anticipate”, “project”, “estimate”, “intend”, “continue” or “believe” (or the negatives thereof) or other variations thereof. Due to various risks and uncertainties, actual events or results or actual performance may differ materially and are subject to change at any time in response to changing circumstances and industry developments. This information and data has been prepared from sources believed reliable, but the accuracy and completeness of the information cannot be guaranteed and is not a complete summary or statement of all available data. FPA does not undertake to update any forward-looking statement because of new information, future developments, or otherwise.
Portfolio composition will change due to ongoing management of the Fund. References to individual financial instruments or sectors are for informational purposes only and should not be construed as recommendations by the Fund or the portfolio managers. It should not be assumed that future investments will be profitable or will equal the performance of the financial instrument or sector examples discussed. The portfolio holdings as of the most recent quarter-end may be obtained at fpa.com.
Investing in closed‐end funds involves risk, including loss of principal. Closed‐end fund shares may frequently trade at a discount (less than) or premium (more than) to their net asset value. If the Fund’s shares trade at a premium to net asset value, there is no assurance that any such premium will be sustained for any period of time and will not decrease, or that the shares will not trade at a discount to net asset value thereafter.
Capital markets are volatile and can decline significantly in response to adverse issuer, political, regulatory, market, or economic developments. It is important to remember that there are risks inherent in any investment and there is no assurance that any investment or asset class will provide positive performance over time.
The Fund may purchase foreign securities, including American Depositary Receipts (ADRs) and other depositary receipts, which are subject to interest rate, currency exchange rate, economic and political risks; these risks may be heightened when investing in emerging markets. Non‐U.S. investing presents additional risks, such as the potential for adverse political, currency, economic, social or regulatory developments in a country, including lack of liquidity, excessive taxation, and differing legal and accounting standards. Non‐U.S. securities, including American Depositary Receipts (ADRs) and other depositary receipts, are also subject to interest rate and currency exchange rate risks.
The return of principal in a fund that invests in fixed income instruments is not guaranteed. The Fund’s investments in fixed income instruments have the same issuer, interest rate, inflation and credit risks that are associated with underlying fixed income instruments owned by the Fund. Such investments may be secured, partially secured or unsecured and may be unrated, and whether or not rated, may have speculative characteristics. The market price of the Fund’s fixed income investments will change in response to changes in interest rates and other factors.
Generally, when interest rates go up, the value of fixed income instruments, such as bonds, typically go down (and vice versa) and investors may lose principal value. Credit risk is the risk of loss of principal due to the issuer’s failure to repay a loan. Generally, the lower the quality rating of an instrument, the greater the risk that the issuer will fail to pay interest fully and return principal in a timely manner. If an issuer defaults, the security may lose some or all its value. Lower-rated bonds, convertible securities and other types of debt obligations involve greater risks than higher rated bonds.
Mortgage-related and asset-backed securities are subject to prepayment risk, can be highly sensitive to changes in interest rates, and are subject to credit risk/risk of default on the underlying assets. Convertible securities are generally not investment grade and are subject to greater credit risk than higher‐rated investments. High-yield securities can be volatile and subject to much higher instances of default. The Fund may experience increased costs, losses and delays in liquidating underlying securities should the seller of a repurchase agreement declare bankruptcy or default.
The ratings agencies that provide ratings are Standard & Poor’s (“S&P”), Fitch, Moody’s, Kroll, DBRS, and any other nationally recognized statistical rating organization (“NRSRO”). Credit ratings range from AAA (highest) to D (lowest). Bonds rated BBB or above are considered investment grade (IG). Credit ratings of BB and below are lower-rated securities (junk bonds). High-yielding, non-investment-grade bonds (junk bonds) (HY) involve higher risks than investment-grade bonds. Bonds with credit ratings of CCC or below have high default risk.
Private placement securities are securities that are not registered under the federal securities laws and are generally eligible for sale only to certain eligible investors. Private placements may be illiquid, and thus more difficult to sell, because there may be relatively few potential purchasers for such investments, and the sale of such investments may also be restricted under securities laws.
The Fund may use leverage. While the use of leverage may help increase the distribution and return potential of the Fund, it also increases the volatility of the Fund’s net asset value (NAV), and potentially increases volatility of its distributions and market price. There are costs associated with the use of leverage, including ongoing dividend and/or interest expenses. There also may be expenses for issuing or administering leverage. Leverage changes the Fund’s capital structure through the issuance of preferred shares and/or debt, both of which are senior to the common shares in priority of claims. If short-term interest rates rise, the cost of leverage will increase and likely will reduce returns earned by the Fund’s common stockholders.
Value style investing presents the risk that the holdings or securities may never reach their full market value because the market fails to recognize what the portfolio management team considers the true business value or because the portfolio management team has misjudged those values. In addition, value style investing may fall out of favor and underperform growth or other styles of investing during given periods.
Distribution Rate
Distributions may include the net income from dividends and interest earned by fund securities, net capital gains, or in certain cases it may include a return of capital. The Fund may also pay a special distribution at the end of a calendar year to comply with federal tax requirements. All mutual funds, including closed-end funds, periodically distribute profits they earn to investors. By law, if a fund has net gains from the sale of securities, or if it earns dividends and interest from securities, it must pass substantially all of those earnings to its shareholders or it will be subject to corporate income taxes and excise taxes. These taxes would, in effect, reduce investors’ total return. First Pacific Advisors, LP does not provide legal, accounting, or tax advice.
The Fund’s distribution rate may be affected by numerous factors, including changes in realized and projected market returns, Fund performance, and other factors. There can be no assurance that a change in market conditions or other factors will not result in a change in the Fund’s distribution rate at a future time.
Index Definitions
Comparison to any index is for illustrative purposes only and should not be relied upon as a fully accurate measure of comparison. The Fund may be less diversified than the indices noted herein and may hold non-index securities or securities that are not comparable to those contained in an index. Indices will hold positions that are not within the Fund’s investment strategy. Indices are unmanaged and do not reflect any commissions, transaction costs, or fees and expenses which would be incurred by an investor purchasing the underlying securities and which would reduce the performance in an actual account. You cannot invest directly in an index. The Fund does not include outperformance of any index in its investment objectives.
Bloomberg U.S. Aggregate Bond Index provides a measure of the performance of the U.S. investment-grade bond market, which includes investment-grade U.S. Government bonds, investment-grade corporate bonds, mortgage pass-through securities and asset-backed securities that are publicly offered for sale in the United States. The securities in the Index must have at least one year remaining in maturity. In addition, the securities must be denominated in U.S. dollars and must be fixed rate, nonconvertible, and taxable.
MSCI ACWI NR USD Index (MSCI ACWI) is an unmanaged free float-adjusted market capitalization weighted index that is designed to measure the equity market performance of developed and emerging markets. Net Return (NR) indicates that withholding taxes are applied to dividend reinvestments. MSCI uses the withholding tax rate applicable to non-resident institutional investors that do not benefit from double taxation treaties.
Standard & Poor’s 500 Stock Index (S&P 500) is a capitalization-weighted index which covers industrial, utility, transportation and financial service companies, and represents approximately 75% of the New York Stock Exchange (NYSE) capitalization and 30% of NYSE issues. The S&P 500 is considered a measure of large capitalization stock performance.
60% MSCI ACWI / 40% BBG U.S. Aggregate Bond Index is a hypothetical combination of unmanaged indices and comprises 60% MSCI ACWI Index and 40% Bloomberg U.S. Aggregate Bond Index.
60% S&P 500 / 40% BBG U.S. Aggregate Bond Index is a hypothetical combination of unmanaged indices and comprises 60% S&P 500 Index and 40% Bloomberg U.S. Aggregate Bond Index.
Bloomberg U.S. High Yield Index measures the market of USD-denominated, non-investment-grade, fixed-rate, taxable corporate bonds.
Bloomberg U.S. High Yield BB ex Energy Index measures the market of USD-denominated, non-investment-grade, fixed-rate, taxable BB-rated corporate bonds excluding the energy sector.
Glossary of Terms
Capital expenditures (CapEx) are the funds companies allocate to acquire, upgrade, and maintain essential physical assets like property, technology, or equipment, crucial for expanding operational capacity and securing long-term economic benefits.
Credit is defined as investments rated BBB or lower, including non-rated investments.
Discount to Net Asset Value (NAV) is a pricing situation when a closed-end fund’s market trading price is lower than its daily net asset value (NAV).
Dividend Yield is the dividend per share divided by the price per share.
Earnings Per Share (EPS) is calculated as a company’s profit divided by the outstanding shares of its common stock.
Equity-like returns refer to long-term returns that are comparable to those generated by equity markets.
High-Yield (HY) Bond is a high-paying bond with a lower credit rating than investment-grade corporate bonds, Treasury bonds and municipal bonds. Because of the higher risk of default, these bonds pay a higher yield than investment-grade bonds.
Investment Grade (IG) is a rating that indicates that a bond has a relatively low risk of default.
Market Capitalization refers to the total dollar market value of a company’s outstanding shares of stock. Commonly referred to as “market cap,” it is calculated by multiplying the total number of a company’s outstanding shares by the current market price of one share.
Market Price is the price at which investors may purchase or sell shares of Source Capital, which is an exchange-traded closed-end fund. Market price is determined in the open market by buyers and sellers, based on supply and demand. The difference between the market price and the NAV (Premium/Discount) is expressed as a percentage of NAV.
Net Asset Value (NAV) is the market value of one share of the Fund. The NAV is calculated by subtracting the Fund’s liabilities from the value of the Fund’s total assets and dividing it by the number of the Fund’s outstanding shares.
On-the-run Treasuries are the most recently issued U.S. Treasury bonds, notes, or bills of a specific maturity and can serve as benchmarks for pricing other financial instruments.
Price/Earnings Ratio (P/E) is the price of a stock divided by its earnings per share. P/E is calculated using weighted harmonic averaging, which helps avoid extreme results that may occur due to small relative numbers, and excludes Real Estate Investment Trusts (REITs). 12-Month Trailing P/E is based on the last 12 months of actual earnings. 12-Month Forward P/E utilizes forward earnings expectations over the next 12 months to calculate the ratio.
Risk-free rate of return is the theoretical rate of return of an investment with zero risk. The risk-free rate represents the interest an investor would expect from an absolutely risk-free investment over a specified period of time.
Spread reflects the quoted spread of a bond that is relative to the security off which it is priced, typically an on-the-run treasury.
Yield is the discount rate that links the bond’s cash flows to its current dollar price.
Yield to Worst (YTW) is presented gross of fees and reflects the lowest potential yield that can be received on a debt investment without the issuer defaulting. YTW considers the impact of expected prepayments, calls and/or sinking funds, among other things. Average YTW is based on the weighted average YTW of the investments held in the Fund’s portfolio. YTW is only one component of return and may not represent the yield an investor should expect to receive. YTW excludes convertible bonds with a YTW less than the comparable maturity Treasury yield plus the 20-Year average high-yield spread to the Treasury yield, impaired/defaulted bonds, and letters of credit. The indices’ YTWs exclude all convertibles.
©2026 Morningstar, Inc. All Rights Reserved. The information contained herein: (1) is proprietary to Morningstar and/or its content providers; (2) may not be copied or distributed; and (3) is not warranted by Morningstar to be accurate, complete, or timely. Neither Morningstar nor its content providers are responsible for any damages or losses arising from any use of this information. Past performance is no guarantee, nor is it indicative, of future results.