You should consider the Fund’s investment objectives, risks, and charges and expenses carefully before you invest. The Prospectus details the Fund’s objective and policies, charges, and other matters of interest to a prospective investor. Please read the Prospectus carefully before investing. The Prospectus may be obtained by visiting the website at fpa.com, by email at [email protected], toll-free by calling 1-800-982-4372 or by contacting the Fund in writing.
Average Annual Total Returns (%)
| As of September 30, 2026 | Since Inception* | 5 Yr | 3 Yr | 1 Yr | YTD | QTD |
|---|---|---|---|---|---|---|
| FPA Flexible Fixed Income (FPFIX) | 3.48 | 3.38 | 5.01 | -0.26 | -1.47 | -1.88 |
| Bloomberg U.S. Universal | 1.80 | -0.26 | 4.53 | -1.45 | -2.62 | -3.37 |
| CPI + 200 | 5.84 | 6.29 | 5.13 | 5.80 | 4.70 | 1.63 |
*Inception date was December 31, 2018. Index data source: Morningstar.
Past performance is no guarantee of future results and current performance may be higher or lower than the performance shown. This data represents past performance and investors should understand that investment returns and principal values fluctuate, so that when you redeem your investment it may be worth more or less than its original cost. Current month-end performance data, which may be higher or lower than the performance data quoted, may be obtained at fpa.com or by calling toll-free, 1-800-982-4372.
The FPA Flexible Fixed Income Fund (“Fund”) performance reflects the Institutional Class and is calculated on a total return basis which includes reinvestment of all distributions and is net of all fees and expenses. Fund returns do not reflect the deduction of taxes that a shareholder would pay on Fund distributions or the redemption of Fund shares, which would lower these figures. Comparison to any index is for illustrative purposes only. The Fund does not include outperformance of any index or benchmark in its investment objectives. An investor cannot invest directly in an index.
As of the most recent prospectus, the Fund’s total expense ratio is 0.63% for the Institutional Class, 0.65% for the Advisor Class, and 0.81% for the Investor Class. The net expense ratio is 0.55% for the Institutional Class, 0.60% for the Advisor Class, and 0.65% for the Investor Class. First Pacific Advisors, LP (the “Adviser” or “FPA”), the Fund’s investment adviser, has contractually agreed to reimburse the Fund for Total Annual Fund Operating Expenses (excluding interest, taxes, brokerage fees and commissions payable by the Fund in connection with the purchase or sale of portfolio securities, redemption liquidity service expenses, and extraordinary expenses, including litigation expenses not incurred in the Fund’s ordinary course of business) in excess of 0.554% of the average net assets of the Fund attributable to the Institutional Class, 0.604% of the average net assets of the Fund attributable to the Advisor Class, and 0.654% of the average net assets of the Fund attributable to the Investor Class for the one-year period ending April 30, 2027. Any expenses reimbursed to the Fund by FPA during any of the previous 36 months may be recouped by FPA, provided the Fund’s Total Annual Fund Operating Expenses do not exceed 0.64% of the average net assets of the Fund attributable to the Institutional Class, 0.74% of the average net assets of the Fund attributable to the Advisor Class, and 0.79% of the average net assets of the Fund attributable to the Investor Class for any subsequent calendar year, regardless of whether there is a then-effective higher expense limit. This agreement may only be terminated earlier by the Fund’s Board of Trustees (the “Board”) or upon termination of the Advisory Agreement.
Please see important disclosures at the end of this commentary.
Dear Shareholder:
FPA Flexible Fixed Income Fund (the “Fund”) returned -1.88% in third quarter of 2026.
| 9/30/2026 | |
|---|---|
| Yield-to-worst1 | 5.36% |
| Subsidized/Unsubsidized 30-day SEC Yield1 | 3.74%/3.66% |
| Effective Duration | 3.60 Years |
| Spread Duration | 2.00 Years |
| High Quality Exposure2 | 96% |
| Credit Exposure3 | 4% |
¹ As of September 30, 2026, the Fund’s subsidized/unsubsidized 30-day SEC standardized yield (“SEC Yield”) was 3.74%/3.66% respectively. The SEC Yield calculation is an annualized measure of the Fund’s dividend and interest payments for the last 30 days, less the Fund expenses. Subsidized yield reflects fee waivers and/or expense reimbursements during the period. Without waivers and/or reimbursements, yields would be reduced. Unsubsidized yield does not adjust for any fee waivers and/or expense reimbursements in effect. The SEC Yield calculation shows investors what they would earn in yield over the course of a 12-month period if the Fund continued earning the same rate for the rest of the year.
Yield-to-worst (“YTW”) is presented gross of fees and reflects the lowest potential yield that can be received on a debt investment without the issuer defaulting. YTW considers the impact of expected prepayments, calls and/or sinking funds, among other things. Average YTW is based on the weighted average YTW of the investments held in the Fund’s portfolio. YTW may not represent the yield an investor should expect to receive.
2 High Quality is defined as investments rated A or higher, Treasuries, and cash and equivalents.
3 Credit is defined as investments rated BBB or lower, including non-rated investments.
Treasury yields increased approximately 60-90 bps across the yield curve over the past few months, leaving yields approximately 80-150 bps higher year-to-date. High yield spreads increased during the quarter, led by an increase in spread for the lowest-rated debt. As an indicator of the core of the high yield market, spreads on BB-rated debt, excluding energy increased from historically low levels at the end of the second quarter but remain low by historical standards. By comparison, spreads on investment grade debt were generally little changed during the quarter, leaving many parts of that market near historically expensive territory. We seek to opportunistically invest in Credit when we believe prices adequately compensate for the risk of permanent impairment of capital and near-term mark-to-market risk. We found a small opportunity in Credit (investments rated BBB or lower) during the quarter but did not find yet meaningful opportunities. Due to low spreads, we focused on buying longer-duration, High Quality bonds (rated single-A or higher) that we believe will enhance both the Fund’s long-term returns and short-term upside-versus-downside return profile.
3Q 2026 Contributors and Detractors4
| ▲ Top contributors | Notable drivers of return |
|---|---|
| Cash and equivalents | Interest income |
| Collateralized Loan Obligations (CLOs) | Interest income; prices on these floating rate bonds did not change meaningfully |
| Recurring revenue loan ABS | Price appreciation and interest income |
| ▼ Top detractors | Notable drivers of return |
|---|---|
| Nominal Treasuries | Price decrease caused by an increase in benchmark yields, partially offset by interest income |
| Agency mortgage pools | Price decrease driven by an increase in benchmark yields and, to a lesser extent, spreads, partially offset by interest income |
| Non-agency RMBS | Price decrease driven by an increase in benchmark yields, partially offset by interest income |
4 This information is not a recommendation for a specific security or sector and these securities/sectors may not be in the Fund at the time you receive this report. The information provided does not reflect all positions purchased, sold or recommended by FPA during the quarter or calendar year. The portfolio holdings as of the most recent quarter-end may be obtained at fpa.com.
Portfolio Activity6
The tables below provide an overview of the portfolio as of September 30, 2026 and June 30, 2026:
| 9/30/2026 | 6/30/2026 | ||
|---|---|---|---|
| Yield-to-worst1 | 5.36% | 4.50% | |
| Effective Duration | 3.60 years | 3.43 years | |
| Spread Duration | 2.00 years | 1.91 years | |
| Average Life | 4.17 years | 3.84 years |
| 9/30/2026 | 6/30/2026 | ||
|---|---|---|---|
| Sector Exposure (% of portfolio) | |||
| ABS | 17.0 | 15.3 | |
| CLO | 1.4 | 1.6 | |
| Corporate | 3.7 | 3.3 | |
| Agency CMBS | 7.3 | 7.3 | |
| Non-Agency CMBS | 4.0 | 4.0 | |
| Agency RMBS | 17.1 | 15.6 | |
| Non-Agency RMBS | 10.0 | 10.3 | |
| Stripped Mortgage-backed | 0.0 | 0.0 | |
| U.S. Treasury Notes | 31.8 | 32.3 | |
| Treasury Inflation-Protected Securities (TIPS) | 4.3 | 1.5 | |
| Cash and equivalents | 3.3 | 8.7 | |
| Total | 100.0 | 100.0 |
6 Portfolio composition will change due to ongoing management of the Fund.
Past performance is no guarantee, nor is it indicative, of future results.
Our investment activity during the quarter included the following:
- Extended the duration of the existing Treasury Note holdings, including buying 7-year maturity Treasury Notes.
- Added to an existing position in 5-year maturity Treasury Inflation Protected Securities (“TIPS”).
- Bought 5-year maturity Treasury Inflation Protected Securities (“TIPS”).
- Bought High Quality bonds with a weighted average life and duration of 5.1 years and 4.4 years, respectively. Meaningful investments included7:
- Agency mortgage pools
- Asset-backed securities (ABS) backed by prime auto loans
- Agency collateralized mortgage obligations (CMOs)
- ABS backed by equipment
- Investment grade corporate bonds
Please see our Q2 2026 commentary8 for a description of our TIPS investment. In short, we are not buying TIPS to express a view on inflation; we have no view. Rather, at the real yields at which we bought TIPS, we believe TIPS offer an attractive short- and long-term return across a range of future inflation rates.
We did not make a meaningful investment in Credit during the quarter.
7 We include investment ideas in which we invested at least 0.25% of the portfolio.
8 https://fpa.com/wp-content/uploads/FPA-Flexible-Fixed-Income-Fund-Commentary-2026-06.pdf
Observations
As shown below, Treasury yields increased during the quarter and year-to-date:
U.S. Treasury Yield Curve
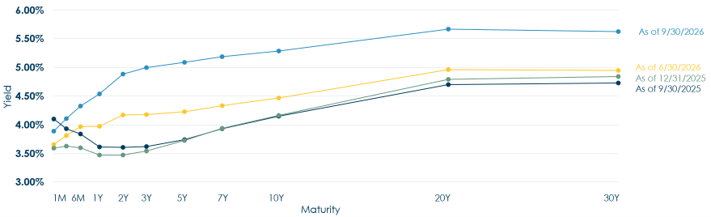
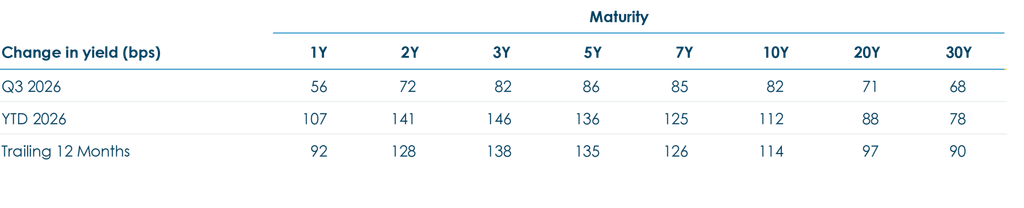
Source: Bloomberg; As of September 30, 2026. For illustrative purposes only.
The increase in market yields caused bond prices to decline over the past few months, with the magnitude of the decline driven by the duration of the bonds in question. The Fund was not immune to this decline. However, importantly, the price of the Fund did not decline because of a permanent impairment of capital. The Fund has relatively little credit risk. Rather, the price of the Fund declined because of temporary, short-term mark-to-market changes in price. We are not surprised by this result. In fact, it is part of the bargain we make as we invest in longer duration bonds. We believe we could hold the Fund’s investments to maturity and the price declines would be recouped over time. However, we also believe that would not be the long-term return-maximizing course of action. Rather, we believe that taking advantage of the increase in yields to buy longer duration bonds could enhance the Fund’s long-term returns.
As a reminder, we do not have a macroeconomic forecast that guides our investment decisions. Making high-conviction interest rate forecasts is challenging under “normal” circumstances, and all bets are off when there are unexpected exogenous events like wars or changes in policy that affect the economy. Instead, valuation guides our investment decisions. With respect to duration, we define value using our duration test, which seeks to identify the longest duration bonds we believe will produce at least a breakeven return over twelve months, assuming yields increase by 100 bps over that period. We illustrate the test below:
Hypothetical 12-month U.S. Treasury Returns
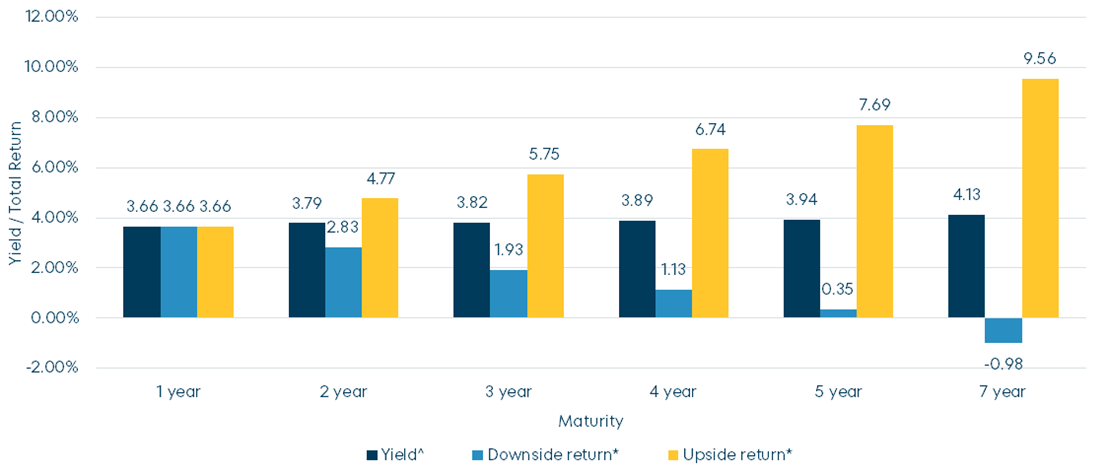
As of September 30, 2026. Source: Bloomberg. This chart illustrates factors that the investment team considers when assessing interest rate risk and shows how interest rate increase could affect investments. ^Yield to Maturity (YTM) is the total return anticipated on a bond if the bond is held until it matures. *Downside return estimates the 12-month total return assuming yields increase by 100 bps over 12 months. Upside return estimates the 12-month total return assuming yields decline by 100 bps over 12 months. Return estimates assume gradual change in yield over 12 months. The hypothetical stress test data provided herein is for illustrative and informational purposes only and is intended to demonstrate the mathematical impact of a hypothetical change in Treasury yields on Treasury returns. This data is not, and is not intended to be representative of, the Fund’s returns. No representation is being made that any account, product or strategy will or is likely to achieve profits, losses, or results similar to those shown. FPA applies a 100-basis point duration test to seek to identify the longest-duration bonds that may produce at least a breakeven return over a 12-month period, assuming a bond’s yield will increase by 100 basis points during that period. The dark blue bars represent actual Treasury yields at various maturities as of June 30, 2026. The light blue bars represent the potential short-term downside return for these bonds in a rising interest rate environment. The yellow bars show the short-term upside potential if rates decrease by 100 basis points over 12 months. Past performance is no guarantee, nor is it indicative, of future results. Please refer to the back of the commentary for important disclosures.
The dark blue bars in the chart above represent the Treasury yield curve as of September 30. The light blue bars represent our “downside” scenario with respect to interest rate risk and estimate the 12-month total return for each Treasury maturity assuming yields increase by 100 bps over twelve months. The yellow bars represent our “upside” scenario and estimate the 12-month total return for each Treasury maturity assuming yields decrease by 100 bps over twelve months.
We do not know whether rates will increase or decrease going forward. We do know that rates could increase or decrease going forward. Thus, the objective of our duration test is to deliver our investors a consistent ability to preserve capital against a short-term increase in yields which we define as a 100 bps increase in yields over a rolling 12-month period. At the same time, when yields are elevated, the longer duration bonds identified by our duration test give us an option on potentially high single digit or low double digit returns if rates decline in the short-term. And long-term, we’re locking in what is historically an attractive yield for multiple years.
To be clear, we do not seek to defend the portfolio from all increases in yields, we make no assumptions about changes in the shape of the yield curve, and we do not seek to defend the portfolio against rate moves that happen over periods of less than a year. We chose 100 bps as our threshold because it covers the majority, but certainly not all, of the historical 12-month changes in yields for 2-10 year maturity Treasuries.
We meet with a number of our investors on a recurring basis as part of their ongoing due diligence. During those meetings, we are often asked whether our investment philosophy has changed. Rest assured it has not – and has not changed in decades – but our execution of that philosophy can and has changed as markets change. Our duration management is a good example of the application of the same philosophy resulting in different outcomes. Indeed, so consistent is our investment philosophy that we can repeat today what we wrote in Q2 2023, the last time rates rose toward today’s levels:
On an absolute basis, we find longer-duration, High Quality bonds attractive for two reasons:
First, we believe that over the long term, investors will benefit from growing their capital at today’s yields for multiple years. One might wonder whether it makes more sense to hold cash or very short-duration bonds instead of longer-duration bonds. If we knew rates will rise further and the timing and magnitude of that increase, then certainly holding onto cash or very short-duration bonds would make a lot of sense. However, we don’t believe we can know such things with a high level of conviction. Therefore, we believe it makes sense to take advantage of yields available today. Thinking about the opportunity cost of this decision helps elucidate the rationale: if yields were to decline by 25 basis points (or 50 basis points, or some other large amount) we believe investors would regret not buying bonds at today’s yields when they had the chance.
Second, we believe longer-duration High Quality bonds offer a more attractive short-term return profile. Bond prices can, of course, move between today and a bond’s maturity so we want to be mindful of duration risk and short-term returns. Employing the duration test described earlier, if yields in the short term were to increase by 100 bps over the next 12 months, we believe these longer-duration investments would produce at least a breakeven return, limit short-term drawdowns, and preserve capital we could then seek to redeploy into higher-yielding investments. Alternatively, if yields were to decline for any reason, longer-duration investments we believe would meaningfully improve the Fund’s short-term total return…we believe longer-duration bonds at today’s yields have a more attractive asymmetry in their short-term upside versus downside return while also locking in an attractive yield (on an absolute basis) for the long term.
We feel the same way today. For most of 2026, five-year maturity bonds were the focus of our duration test because it was the longest maturity that produced at least a breakeven return in our rising interest rate scenario; maturities longer than five years generally produced an expected short-term loss under our duration test. For example, at December 31, 2025, our duration test showed that the 5-year Treasury could produce a downside return of 0.12% and upside return of 7.49%. Due to the increase in yields over the past nine months, at September 30, the 7-year Treasury could produce a similar downside return of 0.24% but with an upside return potential of 10.45%, an approximately 300 bps increase in upside return versus the 5-year Treasury at December 31, 2025!9 When rates increase, the return asymmetry on longer duration bonds improves, which we find attractive.
Disciplined risk management can leave investors well-positioned to take advantage of the investment opportunities created by a higher yield environment: we took advantage of the increase in yields during the quarter to buy 7-year maturity Treasuries and other longer-duration investments that now pass our duration test. We may continue to make similar investments in the coming quarters to the extent we can continue to buy longer-duration investments at yields that pass our test. In doing so, we believe we can retain the Fund’s protection against a 100 bps increase in yields while improving the Fund’s short- and long-term return profile.
We could choose not to take advantage of lower prices and instead maintain a relatively consistent duration at all times, regardless of the level of interest rates, as do other fixed income funds, particularly those that track an index. We are not bound by such constraints and the limits they place on producing attractive risk-adjusted returns over the long-term. We believe that active management should avail itself of cheaper markets to enhance the Fund’s risk versus reward, and we believe our duration management process is a means to that end. Looking forward, we recognize that it can be uncomfortable to buy as prices are falling. We are investors in the Fund, so we feel the discomfort firsthand, but we also know that without risk there can be no reward. To help focus our decision-making, we consider the alternative to high yields: low yields. The path to generating high absolute returns in fixed income over the long term is not paved with low yields. We think back to late February of this year, when the 5-year Treasury was trading at a 3.50% yield and we were concerned that our days of buying attractive yield in longer-duration bonds were numbered. We had more angst then than we do today even though yields have increased meaningfully since February. The reasons for that increase are subject to debate. Some reasons are positive – a stronger economy – and some are concerning – war, fiscal concerns, and inflation, to name a few. Regardless, we much prefer a cheaper market versus a more expensive market, and we much prefer a world where we and our investors can earn higher returns. When yields increase, one should be more excited, not less. While our investment approach may not produce the greatest returns every year, over the long-term, consistent execution of the same investment philosophy has resulted in a greater total and risk-adjusted return than the typical nontraditional bond fund, the Aggregate Bond Index or the Universal Index.10 Though past performance is no guarantee of future results, we employ a similar playbook today.
9 Based on hypothetical stress test data. Provided for illustrative and informational purposes only and is intended to demonstrate the mathematical impact of a hypothetical change in Treasury yields on Treasury returns. FPA’s complete active duration management analysis for December 31, 2025 is found at https://fpa.com/wp-content/uploads/FPA-Flexible-Fixed-Income-Fund-Commentary-2025-12.pdf and for September 30, 2026 is found on page 6. This data is not, and is not intended to be representative of, the Fund’s returns.
10 Typical nontraditional bond fund refers to the Morningstar Nontraditional Bond Category Average as of September 30, 2026 Time periods greater than one-year are annualized. As of September 30, 2026, there were the following number of funds in the category: 5 years: 493. Please refer to the end of this commentary for Important Disclosures and a Glossary of Terms.
FPA Flexible Fixed Income Growth of $10,000 Over Five Years
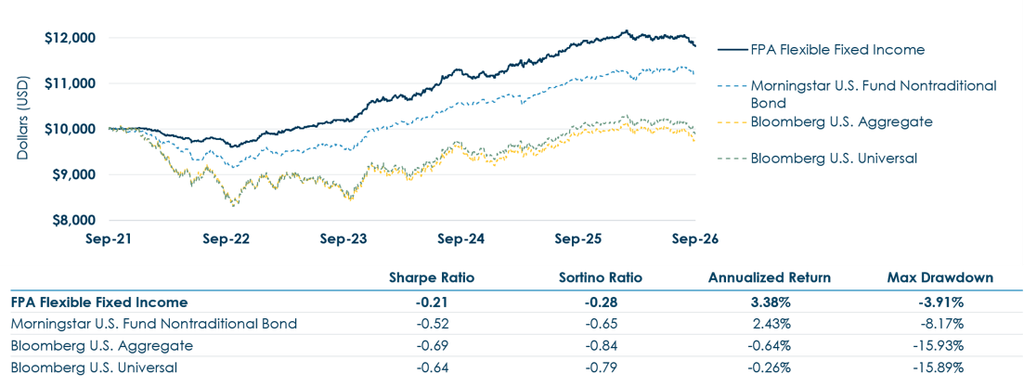
Source: Morningstar Direct. As of 9/30/2026. Performance shown is for the Institutional Class shares (“FPFIX”). FPFIX performance is net of all fees and expenses and includes the reinvestment of distributions. Please see page 1 for additional performance disclosures and definitions. Data provided is from September 30, 2021 to September 30, 2026. This data represents past performance and investors should understand that investment returns and principal values fluctuate, so that if you redeem your investment in the Fund it may be worth more or less than its original cost. Past performance is no guarantee of future results and current performance may be higher or lower than the performance shown. Current month-end performance data for FPFIX, which may be higher or lower than the performance data quoted, may be obtained at fpa.com or by calling toll-free, 1-800-982-4372. FPFIX’s net expense ratio as indicated in its most recent prospectus is 0.55%. Please refer to the end of the commentary for Important Disclosures and a Glossary of Terms.
Elsewhere, as shown below, though spreads in lower-rated debt increased during the quarter, they remain relatively low by historical standards.
Bloomberg U.S. Corporate High Yield Index
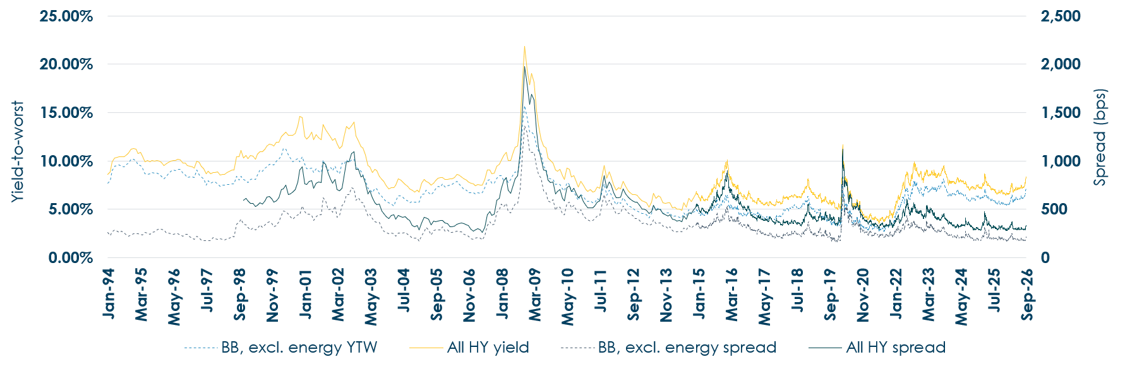
| At 9/30/26 | Spread | Percentile |
|---|---|---|
| All High Yield | 333 bps | 13% |
| BB, ex. Energy | 211 bps | 20% |
Source: Bloomberg. As of September 30, 2026. YTW is Yield-to-Worst. Spread reflects the quoted spread of a bond that is relative to the security off which it is priced, typically an on-the-run Treasury. For illustrative purposes only. A percentile is a statistical measure that indicates the value below which a given percentage of observations in a group of data falls.
Meanwhile, spreads in investment grade debt were little changed over the past few months:
Bloomberg U.S. Aggregate Bond Index
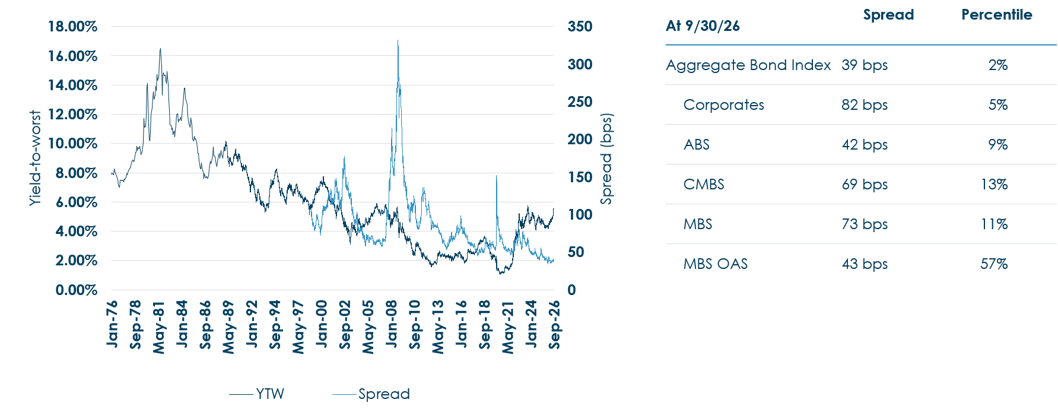
Source: Bloomberg. As of September 30, 2026. YTW is Yield-to-Worst. Spread reflects the quoted spread of a bond that is relative to the security off which it is priced, typically an on-the-run treasury. For illustrative purposes only. A percentile is a statistical measure that indicates the value below which a given percentage of observations in a group of data falls.
Index-level spreads do not determine our investment decisions. Instead we use price (the combination of dollar price, coupon, yield, spread, duration, and loan-to-value) at the individual investment level to guide our investment decisions. We seek to be sellers of glee and buyers of fear. When market optimism causes prices to rise (often reflected in lower spreads and/or lower yields), we become sellers of risk because the reward has decreased. When prices fall due to fear or pessimism (often seen as higher spreads and/or yields), we become buyers of risk because the reward has increased which, consequently, reduces the risk. This applies to duration risk and credit risk. We described above how we apply this mindset to duration risk. As it relates to credit risk, we had been reducing the Fund’s Credit exposure over the past several quarters as spreads compressed. Likewise, we exited our data center and hyperscaler-related investments as spreads compressed to levels we felt no longer offered an attractive return for the risk involved. In recent months, fears about the trajectory of the data center market and hyperscalers’ balance sheets led to an increase in spreads in those markets. This shift created an opportunity for us to initiate11 a position in investment-grade hyperscaler bonds. We are not blind to the balance sheet concerns. We have underwritten that risk with our usual focus on the downside and believe that the potential reward is now worth the risk. Going forward, we believe the Fund is well positioned to take advantage of other opportunities that market turbulence may unearth.
In closing, we reference our Q4 2023 commentary12, in which we said the following:
2023 was just one mile in a marathon…. The Fund was a top performer in 2023, which is great but was not the objective; rather it was a by-product of our investment approach. Much like the fable of the tortoise and the hare, slow and steady wins the race. The Fund may not win each mile of the marathon, but over the past five years the Fund’s performance has placed near the head of the pack. Likewise, 2026 will be just one mile in a marathon. Our goal is not to win every mile but to be in the lead over the long-term.
11 We operate on the assumption that we will never be able to bottom-tick the market and, more likely than not, prices will go lower before they go higher – if they ever go higher. Thus, we say “initiate” above because we try to leave capacity to add to positions at cheaper prices.
12 https://fpa.com/wp-content/uploads/fpa-new-income-fund-commentary-2023-12.pdf
Thank you for your confidence and continued support.
Abhijeet Patwardhan
Portfolio Manager
October 2026
Important Information
This Commentary is for informational and discussion purposes only and does not constitute, and should not be construed as, an offer or solicitation for the purchase or sale of any securities, products or services discussed, and neither does it provide investment advice. Any such offer or solicitation shall only be made pursuant to the Fund’s Prospectus, which supersedes the information contained herein in its entirety.
The views expressed herein and any forward-looking statements are as of the date of the publication and are those of the portfolio management team. Future events or results may vary significantly from those expressed and are subject to change at any time in response to changing circumstances and industry developments. This information and data has been prepared from sources believed reliable, but the accuracy and completeness of the information cannot be guaranteed and is not a complete summary or statement of all available data. You should not construe the contents of this document as legal, tax, accounting, investment or other advice or recommendations.
Portfolio composition will change due to ongoing management of the Fund. References to individual securities or sectors are for informational purposes only and should not be construed as recommendations by the Fund, the portfolio manager, the Adviser, or the distributor. It should not be assumed that future investments will be profitable or will equal the performance of the security or sector examples discussed. The portfolio holdings as of the most recent quarter-end may be obtained at fpa.com.
The statements made herein may be forward-looking and/or based on current expectations, projections, and/or information currently available. Actual results may differ from those anticipated. The portfolio manager and/or FPA cannot assure future results and disclaims any obligation to update or alter any statistical data and/or references thereto, as well as any forward-looking statements, whether as a result of new information, future events, or otherwise. Such statements may or may not be accurate over the long-term.
Investments carry risks and investors may lose principal value. Capital markets are volatile and can decline significantly in response to adverse issuer, political, regulatory, market, or economic developments. The Fund may purchase foreign securities, including depository receipts, which are subject to interest rate, currency exchange rate, economic and political risks; these risks may be elevated when investing in emerging markets. Foreign investments, especially those of companies in emerging markets, can be riskier, less liquid, harder to value, and more volatile than investments in the United States. The securities of smaller, less well-known companies can be more volatile than those of larger companies.
The return of principal in a bond fund is not guaranteed. Bond funds have the same issuer, interest rate, inflation and credit risks that are associated with underlying bonds owned by the Fund. Lower rated bonds, convertible securities and other types of debt obligations involve greater risks than higher rated bonds.
Interest rate risk is the risk that when interest rates go up, the value of fixed income instruments, such as bonds, typically go down and investors may lose principal value. Credit risk is the risk of loss of principal due to the issuer’s failure to repay a loan. Generally, the lower the quality rating of a fixed income instrument, the greater the risk that the issuer will fail to pay interest fully and return principal in a timely manner. If an issuer defaults the fixed income instrument may lose some or all of its value.
Mortgage securities and collateralized mortgage obligations (CMOs) are subject to prepayment risk and the risk of default on the underlying mortgages or other assets; such derivatives may increase volatility. Convertible securities are generally not investment grade and are subject to greater credit risk than higher-rated investments. High yield securities can be volatile and subject to much higher instances of default.
Collateralized debt obligations (“CDOs”), which include collateralized loan obligations (“CLOs”), collateralized bond obligations (“CBOs”), and other similarly structured securities, carry additional risks in addition to interest rate risk and default risk. This includes, but is not limited to: (i) distributions from the underlying collateral may not be adequate to make interest or other payments; (ii) the quality of the collateral may decline in value or default; and (iii) the complex structure of the security may not be fully understood at the time of investment and may produce disputes with the issuer or unexpected investment results. Investments in CDOs are also more difficult to value than other investments.
Value style investing presents the risk that the holdings or securities may never reach their full market value because the market fails to recognize what the portfolio management team considers the true business value or because the portfolio management team has misjudged those values. In addition, value style investing may fall out of favor and underperform growth or other styles of investing during given periods.
The ratings agencies that provide ratings are the Nationally Recognized Statistical Ratings Organizations (NRSROs) DBRS, Inc., Fitch Ratings, Inc., Kroll Bond Rating Agency, Inc., Moody’s Investors Service, Inc., and S&P Global Ratings. Credit ratings range from AAA (highest) to D (lowest). Bonds rated BBB or above are considered investment grade. Credit ratings of BB and below are lower-rated securities (junk bonds). High-yielding, non-investment grade bonds (junk bonds) involve higher risks than investment grade bonds. Bonds with credit ratings of CCC or below have higher default risk.
Please refer to the Fund’s prospectus for a complete overview of the primary risks associated with the Fund.
The Fund is not authorized for distribution unless preceded or accompanied by a current prospectus. The prospectus can be accessed at: https://fpa.com/resources.
Hypothetical Stress-Tested Results
The hypothetical and estimated data provided herein is for illustrative and informational purposes only. No representation is being made that the Fund will or is likely to achieve profits, losses, or results similar to those shown. Hypothetical and estimated results do not reflect trading in actual accounts, and do not reflect the impact that economic, market or other factors may have on the management of the account.
The hypothetical and estimated results as set forth in this commentary do not represent actual results; actual results may significantly differ from the theoretical data being presented. Hypothetical/estimated results have certain inherent limitations. Hypothetical models theoretically may be changed from time to time to obtain more favorable results. There may be sharp differences between simulated or estimated results and the actual results subsequently achieved by any particular account, product or strategy. In addition, simulated/estimated results cannot account for the impact of certain market risks such as a lack of liquidity or default risk. There are numerous other factors related to the markets in general or the implementation of any specific strategy which cannot be fully accounted for in the preparation of simulated or estimated results, all of which can adversely affect actual results.
An investor’s individual portfolio results may vary from any hypothetical or estimated results because of the timing of trades, deposits and withdrawals, the impact of management fees and taxes, market fluctuations, trading costs, cash flows, custodian fees, among other factors. Hypothetical results are not meant to be construed as a prediction of the future return of the Fund. Past performance is no guarantee, nor is it indicative, of future results.
Index Definitions
Comparison to any index is for illustrative purposes only and should not be relied upon as a fully accurate measure of comparison. The Fund will be less diversified than the indices noted herein and may hold non-index securities or securities that are not comparable to those contained in an index. Indices will hold positions that are not within the Fund’s investment strategy. Indices are unmanaged, do not reflect any commissions, fees or expenses which would be incurred by an investor purchasing the underlying securities. The Fund does not include outperformance of any index or benchmark in its investment objectives. Investors cannot invest directly in an index.
Bloomberg U.S. Aggregate Bond Index provides a measure of the performance of the U.S. investment grade bonds market, which includes investment grade U.S. Government bonds, investment grade corporate bonds, mortgage pass-through securities and asset-backed securities that are publicly offered for sale in the United States. The securities in the Index must have at least 1 year remaining in maturity. In addition, the securities must be denominated in U.S. dollars and must be fixed rate, nonconvertible, and taxable.
Bloomberg U.S. Aggregate 1-3 Year Bond Index provides a measure of the performance of the U.S. investment grade bonds market, which includes investment grade U.S. Government bonds, investment grade corporate bonds, mortgage pass-through securities and asset-backed securities that are publicly offered for sale in the United States. The securities in the Index must have a remaining maturity of 1 to 3 years. In addition, the securities must be denominated in U.S. dollars and must be fixed rate, nonconvertible, and taxable.
Bloomberg U.S. Corporate High Yield Index measures the market of USD-denominated, non-investment grade, fixed-rate, taxable corporate bonds. Bloomberg U.S. High Yield BB ex Energy Index measures the market of USD-denominated, non-investment grade, fixed-rate, taxable BB-rated corporate bonds excluding energy sector. Bloomberg U.S. High Yield B ex Energy Index measures the market of USD-denominated, non-investment grade, fixed-rate, taxable B-rated corporate bonds excluding energy sector.
Bloomberg U.S. Corporate High Yield Index ex. Energy measures the market of USD-denominated, non-investment grade, fixed-rate, taxable corporate bonds excluding Energy sector.
Bloomberg U.S. Investment Grade Corporate Index measures the investment grade, fixed-rate, taxable corporate bond market. It includes USD denominated securities publicly issued by US and non-US industrial, utility, and financial issuers.
Bloomberg U.S. Universal Bond Index represents the union of the following Bloomberg indices: U.S. Aggregate Index, the U.S. Corporate High-Yield Index, the 144A Index, the Eurodollar Index, the Emerging Markets Index, and the non-ERISA portion of the CMBS Index. Municipal debt, private placements, and non-dollar-denominated issues are excluded from the Universal Index. The only constituent of the index that includes floating-rate debt is the Emerging Markets Index.
Consumer Price Index (CPI) is an unmanaged index representing the rate of the inflation of the U.S. consumer prices as determined by the U.S. Department of Labor Statistics. This index reflects non-seasonally adjusted returns. There can be no guarantee that the CPI or other indices will reflect the exact level of inflation at any given time.
CPI + 200 bps is created by adding 200 basis points to the annual percentage change in the CPI.
Merrill Lynch Option Volatility Estimate (MOVE) Index reflects the level of volatility in U.S. Treasury futures. The index is considered a proxy for term premiums of U.S. Treasury bonds (i.e., the yield spread between long-term and short-term bonds).
Glossary of Terms
ABS (Asset Backed Securities) are financial securities backed by a loan, lease or receivables against assets other than real estate and mortgage-backed securities.
Average Life (years) is the average length of time that each dollar of unpaid principal on a loan, a mortgage or an amortizing bond remains outstanding.
Basis Point (bps) is equal to one hundredth of one percent, or 0.01%. 100 basis points = 1%.
CLO (Collateralized Loan Obligation) is a single security backed by a pool of debt.
CMBS (Commercial Mortgage Backed Security) is a mortgage-backed security backed by commercial mortgages rather than residential mortgages.
Credit is defined as investments rated BBB or lower, including non-rated investments.
Effective Duration measures the sensitivity of the price to changes in interest rates, incorporating the impact of changes in interest rates on call options and expected cashflows. Calculations for the Fund exclude equity holdings.
A fixed rate bond is a bond that pays the same level of interest over its entire term.
Floating-rate security, also known as a “floater”, is an investment with interest payments that float or adjust periodically based upon a predetermined benchmark.
High Quality is defined as investments rated A or higher, Treasuries, and cash and equivalents.
On-the-run Treasuries are the most recently issued U.S. Treasury bonds, notes, or bills of a specific maturity and can serve as benchmarks for pricing other financial instruments.
Risk-free rate of return is the theoretical rate of return of an investment with zero risk. The risk-free rate represents the interest an investor would expect from an absolutely risk-free investment over a specified period of time.
RMBS (Residential Mortgage Backed Securities) are mortgage-backed securities backed by residential mortgages.
Spread Duration is the sensitivity of the price of a security to changes in its credit spread. The credit spread is the difference between the yield of a security and the yield of a benchmark rate, such as a cash interest rate or government bond yield. Calculations for the Fund exclude equity holdings.
Sortino Ratio is a risk-adjusted performance metric used to determine the additional return for each unit of downside risk. It is calculated by subtracting the risk-free rate from the average return over a period of time and dividing the result by the standard deviation of the negative returns during that period.
©2026 Morningstar, Inc. All Rights Reserved. The information contained herein: (1) is proprietary to Morningstar and/or its content providers; (2) may not be copied or distributed; and (3) is not warranted by Morningstar to be accurate, complete or timely. Neither Morningstar nor its content providers are responsible for any damages or losses arising from any use of this information. Past performance is no guarantee of future results.
The FPA Funds are distributed by Distribution Services, LLC. Distribution Services, LLC and FPA are not affiliated.