You should consider the Fund’s investment objectives, risks, and charges and expenses carefully before you invest. The prospectus details the Fund’s objective and policies, charges, and other matters of interest to a prospective investor. Please read the prospectus carefully before investing. The prospectus may be obtained by visiting the website at fpa.com, by email at [email protected], toll-free by calling 1-800-982-4372, or by contacting the Fund in writing.
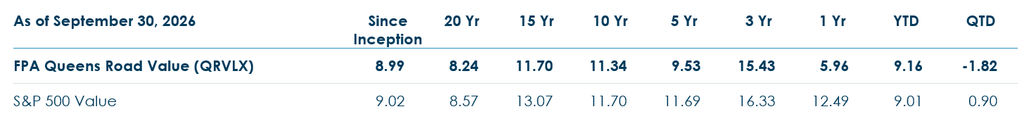
Average Annual Total Returns (%)
Index data source: Morningstar.
Past performance is no guarantee of future results and current performance may be higher or lower than the performance shown. This data represents past performance, and investors should understand that investment returns and principal values fluctuate, so that when you redeem your investment it may be worth more or less than its original cost. Current month-end performance data, which may be lower or higher than the performance data quoted, may be obtained at fpa.com or by calling toll-free, 1-800-982-4372.
The FPA Queens Road Value Fund (“Fund”) commenced operations on June 13, 2002 (Inception date). Periods greater than one year are annualized. Fund performance is shown net of all fees and expenses and includes reinvestment of all distributions. Fund performance does not reflect the deduction of taxes that a shareholder would pay on Fund distributions or the redemption of Fund shares, which would lower these figures. An investor cannot invest directly in an index.
Prior to November 1, 2020, the performance shown reflects the historical performance of the Fund when Bragg Financial Advisors, Inc. (“BFA”) served as investment adviser of the Fund.
From inception of the Fund to December 31, 2004, BFA and its affiliates voluntarily absorbed certain expenses of the Fund and voluntarily waived its management fee. Had BFA not done this, returns would have been lower during that period. Effective January 1, 2005 through October 31, 2020, BFA had a unitized fee structure that limited operating expenses to 0.95%.
As of the most recent prospectus, the Fund’s total expense ratio is 1.41% and net expense ratio is 0.75%. The adviser has contractually agreed to waive management fees and reimburse the Fund for operating expenses in excess of 0.73% of average daily net assets of the Fund, excluding interest, taxes, brokerage fees and commissions payable by the Fund in connection with the purchase or sale of portfolio securities, fees and expenses of other funds in which the Fund invests, and extraordinary expenses, including litigation expenses not incurred in the Fund’s ordinary course of business, until September 30, 2027. These fee waivers and expense reimbursements are subject to possible recoupment by the adviser from the Fund in future years (within the three years from the date when the amount is waived or reimbursed) if such recoupment can be achieved within the lesser of the foregoing expense limits or the then-current expense limits. This agreement may be terminated only by the Fund’s Board of Trustees (the “Board”), upon written notice to the adviser.
Please see important disclosures at the end of the commentary.
Dear Fellow Shareholders:
FPA Queens Road Value Fund returned -1.82% for the third quarter of 2026. This compares to the S&P 500 Value Index return of 0.90% for the same period. Year to date, the Fund returned 9.16% while the Index returned 9.01%.
Higher financing costs and conflict in the Middle East remained important influences on markets during the quarter.1 Within the S&P 500 Value Index, strength in energy and health care helped offset weakness in industrials, utilities, and consumer-related businesses.2 The benchmark’s modest gain therefore reflected an uneven environment rather than a broad advance in value stocks, with meaningful differences between businesses benefiting from higher energy prices and those facing pressure from rising costs.
Our health care holdings were a source of strength during the quarter, while our financial holdings were relatively steady. However, gains in health care were not enough to offset the pullback in our technology holdings after a strong first half. Having no energy exposure also weighed on our performance relative to the benchmark as oil prices rose more than 30%.1 Our cash position averaged 8% during the quarter.
Trailing Twelve-Month Top and Bottom Contributors (%)3
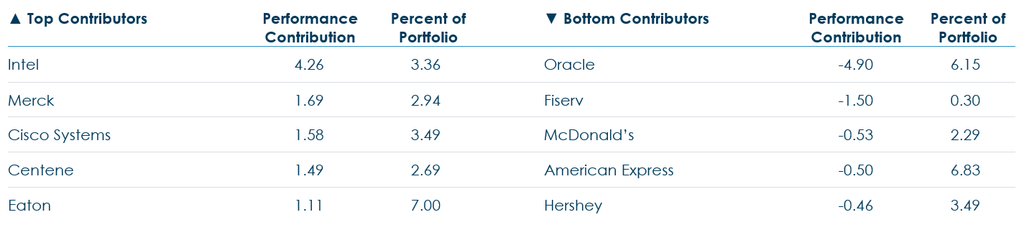
Our top contributors for the quarter4 were Pfizer, Merck, Ameriprise Financial, Danaher, and Prudential Financial. Three of our five largest contributors came from health care. Pfizer rose roughly 20% as investors gained confidence that its largest drag is nearly behind it: COVID-related revenue has declined from about $11 billion in 2024 to roughly $4 billion expected in 2026, leaving the newer and acquired product portfolio to drive results.
Ameriprise benefited from strong third-quarter results with ~12% top-line growth, and in late September its board authorized a new $5.5 billion share repurchase program. Danaher continued to show steady recovery in its bioprocessing and diagnostics businesses; subsequent to quarter end, the company reported core revenue growth excluding respiratory products of 5.5% and raised its full-year earnings guidance.
Our top detractors for the quarter were Intel, American Express, Trane Technologies, Cisco, and General Dynamics. Intel declined about 14% for the quarter, giving back a portion of the sharp gains it made through the spring and early summer. In August, the company sold $20 billion of new stock at $95 per share to fund a capital spending program that now exceeds $20 billion in 2026. CEO Lip-Bu Tan personally purchased roughly $10 million of shares at the same price. Management says demand for server processors far outpaces supply; the question for investors is how much capital it will take to meet it. Semiconductors have long been a cyclical business, and periods of tight supply have often encouraged the industry to build more capacity than demand ultimately required. Artificial intelligence may prove to be a more durable source of demand than past cycles, but the cost of participating keeps rising, and we expect the market to remain sensitive to any sign that spending is getting ahead of returns.
Cisco reported record fiscal fourth-quarter revenue of $17.3 billion, up 18%, but shares fell slightly after gross margin declined 210 basis points on a higher hardware mix and rising memory costs. Trane reported second-quarter revenue growth of 11% and earnings ahead of expectations, yet the shares declined during the quarter.
Higher interest rates and energy prices are a test for every business, and for every portfolio. Our focus remains on strong balance sheets, capable management, durable industry positions, and reasonable valuations — the qualities we believe matter over a full investment cycle.
As always, we appreciate your continued trust in us as stewards of your capital. If you would like to discuss performance or the Fund’s holdings in greater detail, please let us know.
Respectfully,
Steve Scruggs, CFA
Portfolio Manager
1 Tri-Star Trust, “Wild Cards,” Q3 2026 Market Commentary; Investing News Network, “Oil and Gas Price Trends: Q3 2026 Review,” October 2026; Federal Reserve, FOMC statement, September 16, 2026. Sources for the discussion of energy-market disruptions, oil prices, and monetary policy.
2 FactSet, FPA Queens Road Value Fund attribution report for the three months ended September 30, 2026, “QTD (GICS)” worksheet. Sector performance refers to the sector components of the S&P 500 Value Index, not the broader S&P 500. The discussion of the uneven market environment reflects the portfolio manager’s interpretation of these results.
3 Reflects the top and bottom contributors to the Fund’s performance based on preliminary contribution to return for the trailing twelve months (TTM) period ending September 30, 2026. Contribution is presented gross of investment management fees, transaction costs, and Fund operating expenses, which if included, would reduce the returns presented. Portfolio weights represent the average weights over the periods noted. A copy of the methodology used and a list of every holding’s contribution to the overall Fund’s performance during the quarter to date (QTD) and TTM is available by contacting [email protected]. It should not be assumed that recommendations made in the future will be profitable or will equal the performance of the securities listed. Totals may not sum due to rounding. Note: September 30, 2026 company descriptions were developed by the investment team and unless otherwise noted reflect the most recent data made available by the companies or third-party research firms the investment team believes to be reliable.
4 The following positions represented the stated percentages of portfolio assets as of September 30, 2026: Pfizer (3.9%), Merck (3.6%), Ameriprise Financial (5.4%), Danaher (2.5%), Prudential Financial (2.1%), Intel (5.7%), American Express (6.1%), Trane Technologies (7.5%), Cisco (4.0%), and General Dynamics (4.8%).
Important Information
This Commentary is for informational and discussion purposes only and does not constitute, and should not be construed as, an offer or solicitation for the purchase or sale of any securities, products or services discussed, and neither does it provide investment advice. Any such offer or solicitation shall only be made pursuant to the Fund’s prospectus, which supersedes the information contained herein in its entirety. This Commentary does not constitute an investment management agreement or offering circular.
The statements contained herein reflect the opinions and views of the portfolio manager as of the date written, are subject to change without notice, and may be forward-looking and/or based on current expectations, projections, and/or information currently available. Such information may not be accurate over the long term. These views may differ from those of other portfolio managers and analysts of the firm as a whole and are not intended to be a forecast of future events, a guarantee of future results or investment advice.
Portfolio composition will change due to ongoing management of the Fund. References to individual securities or sectors are for informational purposes only and should not be construed as recommendations by the Fund, the portfolio manager, the Adviser, the Sub-Adviser or the distributor. It should not be assumed that future investments will be profitable or will equal the performance of the security or sector examples discussed. The portfolio holdings as of the most recent quarter-end may be obtained at fpa.com.
Future events or results may vary significantly from those expressed and are subject to change at any time in response to changing circumstances and industry developments. The information and data contained herein have been prepared from sources believed reliable, but the accuracy and completeness of the information cannot be guaranteed and is not a complete summary or statement of all available data.
The information contained herein is not complete, may change, and is subject to, and is qualified in its entirety by, the more complete disclosures, risk factors, and other information contained in the Fund’s prospectus and Statement of Additional Information. The information is furnished as of the date shown. No representation is made with respect to its completeness or timeliness. The information is not intended to be, nor shall it be construed as, investment advice or a recommendation of any kind.
Certain statements contained herein may be forward-looking and/or based on current expectations, projections, and information currently available. Actual events or results may differ materially from those we anticipate, or the actual performance of any investments described herein may differ from those reflected or contemplated in such forward-looking statements, due to various risks and uncertainties. We cannot assure future results and disclaim any obligation to update or alter any forward-looking statements, whether as a result of new information, future events, or otherwise. Such statements may or may not be accurate over the long term. Statistical data or references thereto were taken from sources which we deem to be reliable, but their accuracy cannot be guaranteed.
The reader is advised that the Fund’s investment strategy includes active management with corresponding changes in allocations from one period of time to the next. Therefore, any data with respect to investment allocations as of a given date is of limited use and may not be reflective of the portfolio manager’s more general views with respect to proper geographic, instrument and/or sector allocations. The data is presented for indicative purposes only and, as a result, may not be relied upon for any purposes whatsoever.
In making any investment decision, you must rely on your own examination of the Fund, including the risks involved in an investment. Investments mentioned herein may not be suitable for all recipients and in each case, potential investors are advised not to make any investment decision unless they have taken independent advice from an appropriately authorized advisor. An investment in any security mentioned herein does not guarantee a positive return as securities are subject to market risks, including the potential loss of principal. You should not construe the contents of this document as legal, tax, investment or other advice or recommendations.
Fund performance presented is calculated on a total return basis, which includes the reinvestment of all income, plus realized and unrealized gains/losses, if applicable. Unless otherwise indicated, performance results are presented on a net of fees basis and reflect the deduction of, among other things: management fees, brokerage commissions, operating and administrative expenses, and accrued performance fee/allocation, if applicable.
The information provided herein is based upon data existing as of the date(s) of the report and has not been audited or reviewed. While we believe the information to be accurate, it is subject in all respects to adjustments that may be made after proper review and reconciliation.
Investments carry risks and investors may lose principal value. Capital markets are volatile and can decline significantly in response to adverse issuer, political, regulatory, market, or economic developments. Small and mid-cap stocks involve greater risks, and they can fluctuate in price more than larger company stocks. You risk paying more for a security than you received from its sale. Groups of stocks, such as value and growth, go in and out of favor, which may cause certain funds to underperform other equity funds. The value of an individual security can be more volatile than the market as a whole and can perform differently than the value of the market as a whole.
The prices of securities held by the Fund may decline in response to certain events taking place around the world, including those directly involving the companies whose securities are owned by the Fund. Securities in the Fund’s portfolio may underperform due to inflation (or expectations for inflation), interest rates, global demand for particular products or resources, natural disasters, pandemics, epidemics, terrorism, regulatory events and governmental or quasi-governmental actions. There is a risk that you may lose money by investing in the Fund.
Value style investing presents the risk that the holdings or securities may never reach their full market value because the market fails to recognize what the portfolio management team considers the true business value or because the portfolio management team has misjudged those values. In addition, value style investing may fall out of favor and underperform growth or other styles of investing during given periods.
Please refer to the Fund’s prospectus for a complete overview of the primary risks associated with the Fund.
©2026 Morningstar, Inc. All Rights Reserved. The Morningstar information contained herein: (1) is proprietary to Morningstar and/or its content providers; (2) may not be copied or distributed; and (3) is not warranted by Morningstar to be accurate, complete, or timely. Neither Morningstar nor its content providers are responsible for any damages or losses arising from any use of this information. Past performance is no guarantee of future results.
The FPA Funds are distributed by Distribution Services, LLC. Distribution Services, LLC and FPA are not affiliated.
Index Definitions
The Fund will typically be less diversified than the indices noted herein and may hold non-index securities or securities that are not comparable to those contained in an index. Indices will hold positions that are not within the Fund’s investment strategy. Indices are unmanaged and do not reflect any commissions, transaction costs, or fees and expenses which would be incurred by an investor purchasing the underlying securities and which would reduce the performance in an actual account. You cannot invest directly in an index.
Standard & Poor’s 500 Stock Index (S&P 500) is a capitalization-weighted index which covers industrial, utility, transportation and financial service companies, and represents approximately 75% of the New York Stock Exchange (NYSE) capitalization and 30% of NYSE issues. The S&P 500 is considered a measure of large capitalization stock performance.
S&P 500 Value Index is a subset of the S&P 500 index. Companies within the index are ranked based on growth and value factors including three-year change in earnings price/share, three-year sales/share growth rate, momentum, book value/price ratio, earnings/price ratio, sales/price ratio. The companies at the bottom of this list, that have a higher Value Rank, comprising 33% of the total index market capitalization, are designated as the Value basket.